This guide covers the key differences between ETFs and index funds in 2026 — including cost, tax efficiency, trading mechanics, and which works best inside a Roth IRA, 401(k), or taxable account.
If you have ever typed “should I buy an ETF or an index fund” into Google and come away more confused than when you started, you are not alone. The terminology is genuinely confusing — partly because the financial industry uses these terms inconsistently, and partly because the answer depends on a distinction most articles bury at the bottom. This guide explains the ETF vs index fund difference in plain English — and tells you exactly which to choose for your situation.
What Is an Index Fund?
An index fund is any investment fund — ETF or mutual fund — that passively tracks a market index rather than trying to beat it. The S&P 500 is the most common example: an S&P 500 index fund holds all 500 companies in the same proportions as the index, automatically rebalancing when the index changes.
The key word is passively. No fund manager is picking stocks or timing the market. The fund simply mirrors the index mechanically. This approach has beaten more than 90% of actively managed funds over 15-year periods, according to S&P’s SPIVA data — at a fraction of the cost.
Index funds come in two structures: ETFs (exchange-traded funds, which trade like stocks) and mutual funds (which are priced once daily). When most people say “index fund,” they mean the mutual fund version — but technically, a VTI ETF is also an index fund.
What Is an ETF?
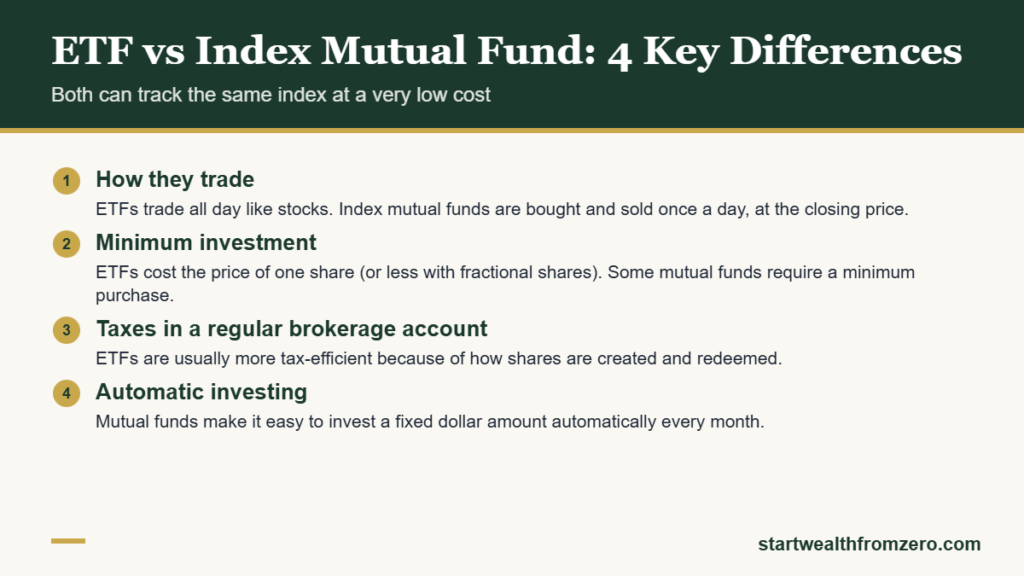
An ETF (exchange-traded fund) is a fund structure — it describes how the fund is bought and sold, not what it holds. ETFs trade on a stock exchange throughout the day at market prices, just like individual stocks. You buy a specific number of shares at whatever price they are trading at that moment.
Most ETFs track a market index (making them index ETFs), but not all. There are actively managed ETFs where a portfolio manager selects holdings — these are closer to traditional mutual funds in strategy, just wrapped in ETF structure. When comparing “ETF vs index fund,” most people are actually comparing index ETFs vs index mutual funds — and that comparison is what this article covers.
ETF vs Index Fund: Side-by-Side Comparison
| ETF (e.g. VTI, VOO) | Index Mutual Fund (e.g. FZROX, FXAIX) | |
|---|---|---|
| How you buy | By the share, like a stock, at market price | By dollar amount at end-of-day price |
| When trades execute | Anytime market is open (9:30am–4pm ET) | Once per day at market close |
| Minimum investment | Price of 1 share (VTI ≈ $260, VOO ≈ $510) | $0 at Fidelity and Schwab |
| Fractional shares | At most major brokers (Fidelity, Schwab, Robinhood) | Always — buy any exact dollar amount |
| Dollar-cost averaging | Works with fractional shares; slightly less seamless | Native — set exact amount and schedule |
| Tax efficiency | Slightly better in taxable accounts | Good, minimal capital gains distributions |
| Expense ratio (best available) | 0.00% (some SoFi ETFs) to 0.03% (VTI, SCHB) | 0.00% (FZROX) to 0.015% (FXAIX) |
| Trading costs | $0 at most brokers; bid-ask spread is tiny | $0, no bid-ask spread |
| Best account type | Taxable brokerage accounts | Roth IRA, 401(k), automatic investing |
| Long-term performance | Identical — tracking the same index produces the same returns | |
The 5 Differences That Actually Matter
1. Trading flexibility. ETFs trade throughout the day at live prices. Index mutual funds execute once at the end-of-day price. For long-term investors holding for 10–30 years, this difference is irrelevant — buying at 10am vs 4pm on the same day has essentially no impact over a 20-year horizon. If you are tempted to trade frequently because of intraday price visibility, that is actually a point against ETFs — behavioral research consistently shows that more trading produces worse returns.
2. Minimum investment. A traditional Vanguard mutual fund like VTSAX requires a $3,000 minimum. The equivalent Vanguard ETF (VTI) requires only the price of one share (~$260). However, at Fidelity and Schwab, popular index mutual funds like FZROX and SWTSX have $0 minimums — eliminating this difference entirely.
3. Dollar-cost averaging. Index mutual funds win here. If you want to invest exactly $200 every two weeks automatically, an index fund executes cleanly — you always invest exactly $200. ETFs require buying whole shares or fractional shares; most major brokers now support fractional ETF shares, but the automation is marginally less seamless. For set-it-and-forget-it monthly investing in a Roth IRA, index funds are the easier choice.
4. Tax efficiency. ETFs have a structural advantage in taxable brokerage accounts due to the “in-kind” creation/redemption mechanism: when large institutional investors redeem ETF shares, they receive actual stocks rather than cash, which means the fund does not need to sell holdings and trigger capital gains. Index mutual funds occasionally distribute small capital gains at year-end, which creates a taxable event for all shareholders. In practice, Fidelity and Vanguard’s index funds distribute minimal capital gains — but ETFs are structurally superior here, particularly for large balances in taxable accounts.
5. Expense ratios. The gap has essentially closed. According to the Investment Company Institute, index mutual funds averaged 0.05% in 2025, while index ETFs averaged 0.14%. But this average is skewed by older, more expensive funds — the cheapest options in both categories are now at or near 0%. FZROX (mutual fund) has a 0% expense ratio. VTI (ETF) charges 0.03%. Neither will meaningfully impact returns.
What ETFs and Index Funds Have in Common (The Part That Matters Most)
All the differences above pale in comparison to what these two investment types share:
- Passive management. Neither requires a fund manager picking stocks. Both mechanically track an index, which is why they beat 90%+ of actively managed funds over 15-year periods.
- Broad diversification. One purchase gives you exposure to hundreds or thousands of companies. VTI and FZROX both hold approximately 3,600 US stocks — the entire US stock market.
- Low cost. The lowest-cost ETFs and index funds charge 0–0.03% per year. Actively managed funds typically charge 0.5–1.5%. On a $100,000 portfolio over 20 years, that fee difference compounds to over $50,000.
- Identical long-term performance. FXAIX (S&P 500 mutual fund) and VOO (S&P 500 ETF) track the same index. Their 10-year returns are within 0.01% of each other. The structure does not change the returns.
The choice between an ETF and an index fund is one of the least important decisions you will make as an investor. The most important decisions — how much you save, how early you start, and whether you stay invested during downturns — dwarf the impact of fund structure.
Tax Efficiency: When It Actually Matters
The tax efficiency advantage of ETFs only matters in one specific situation: a taxable brokerage account. In a Roth IRA, 401(k), HSA, or any other tax-advantaged account, this difference is completely irrelevant — gains compound tax-free or tax-deferred regardless of fund structure.
In a taxable account, the ETF’s in-kind redemption mechanism avoids the capital gains distributions that index mutual funds occasionally generate. The Vanguard Admiral share class has historically distributed very small capital gains (sometimes zero), but Fidelity’s mutual funds including FZROX and FXAIX have also been clean. The ETF advantage is real but often modest in practice — and only becomes significant at large balances ($250,000+) held for long periods in taxable accounts.
Rule of thumb: If your investments are in a Roth IRA or 401(k) — which they should be before you open a taxable account — ignore the tax efficiency argument entirely. Use our Investment Return Calculator to compare how different fee levels affect your final balance over time.
Which Should You Choose? A Simple Framework
The answer depends on where you are investing, not on any inherent quality of one structure over another:
| Your situation | Best choice | Specific fund |
|---|---|---|
| 401(k) at your employer | Whatever is available with the lowest expense ratio | Look for “S&P 500 index” or “total market index” in the fund list |
| Roth IRA at Fidelity | Index mutual fund | FZROX (0.00%) or FXAIX (0.015%) |
| Roth IRA at Vanguard | ETF | VTI (0.03%) or VOO (0.03%) |
| Roth IRA at Schwab | Index mutual fund or ETF | SWTSX (0.03%) or SCHB ETF (0.03%) |
| Taxable brokerage account | ETF (tax efficiency) | VTI, SCHB, or VOO |
| Automatic fixed-amount investing | Index mutual fund | FZROX, FXAIX, SWTSX |
If you are just starting out: open a Roth IRA at Fidelity, invest in FZROX (0% fee, total US market), set up an automatic monthly contribution, and do not think about it again for 30 years. This is the optimal setup for most beginners, and the question of ETF vs index fund simply does not arise. Read our full Roth IRA for Beginners guide to open one in 10 minutes.
Ready to buy your first fund? Follow our step-by-step guide to investing in index funds, or see how to invest $1,000 as a beginner.
Best Index Funds and ETFs for Beginners in 2026
| Fund | Type | What it tracks | Expense ratio | Available at |
|---|---|---|---|---|
| FZROX | Index mutual fund | Total US stock market (~3,600 stocks) | 0.00% | Fidelity only |
| FXAIX | Index mutual fund | S&P 500 (500 largest US companies) | 0.015% | Fidelity only |
| VTI | ETF | Total US stock market (~3,600 stocks) | 0.03% | Any broker |
| VOO | ETF | S&P 500 | 0.03% | Any broker |
| SCHB | ETF | Total US stock market (~2,500 stocks) | 0.03% | Any broker |
| SWTSX | Index mutual fund | Total US stock market | 0.03% | Schwab only |
| VXUS | ETF | International stocks (ex-US) | 0.07% | Any broker |
| BND | ETF | US bonds (for stability near retirement) | 0.03% | Any broker |
For a beginner starting today with a 20–30 year time horizon, a single fund — FZROX, VTI, or VOO — is a complete, well-diversified portfolio. Adding international exposure (VXUS) and eventually bonds (BND) as you approach retirement adds diversification, but the single-fund approach is not wrong. Simplicity beats complexity for most investors.
Common Mistakes When Comparing ETFs and Index Funds
- Assuming all ETFs are index funds. They are not — actively managed ETFs (like ARKK) are also ETFs but have high fees and active management. Always check the expense ratio and whether the fund tracks an index before buying.
- Choosing based on fund structure instead of cost. A 0.03% ETF is better than a 0.75% mutual fund. But a 0.00% mutual fund (FZROX) is better than a 0.20% ETF. The expense ratio matters; the structure does not.
- Waiting to invest until you understand the difference perfectly. The difference between buying VTI today and spending another month researching is worth far more in compounding than any structural choice. Start with the lowest-cost option available in your account and refine later.
- Ignoring account type. Putting a tax-inefficient fund in a taxable account while putting a tax-efficient ETF in a Roth IRA is backwards. The tax-efficient vehicle (ETF) belongs in the taxable account; the tax treatment in a Roth makes the structure irrelevant.
Which Is Better for Long-Term Investors: ETF or Index Fund?
For the vast majority of long-term investors, the honest answer is that the difference in outcomes between a low-cost ETF and a comparable index fund is negligible — we’re talking about fractions of a percent annually.
| Your Situation | Better Choice | Why |
|---|---|---|
| Investing through a 401(k) | Index fund | ETFs usually aren’t available in 401(k) plans; index funds are standard |
| Roth IRA at Fidelity | FZROX (index fund) | 0% expense ratio — lower than any ETF equivalent |
| Roth IRA at Vanguard or Schwab | ETF (VTI or SCHB) | Same cost as equivalent index fund, more flexibility |
| Taxable brokerage account | ETF | Better tax efficiency in taxable accounts |
| Investing small amounts regularly | Index fund | Fractional purchases easier; no need to buy whole shares |
| You want to invest exactly $X | Index fund | Mutual funds accept any dollar amount; ETFs require whole shares at most brokers |
The most important variable in any of these decisions isn’t ETF vs index fund — it’s the expense ratio. A 0.03% VTI and a 0.015% FXAIX will both massively outperform a 1% actively managed fund over 30 years. Pick either, keep the fee low, and invest consistently.
For the official definitions and investor protections around both investment types, see the SEC Investor.gov guide to ETFs and mutual funds.
Frequently Asked QuestionsWhat is the main difference between an ETF and an index fund?
An ETF is a fund structure (traded like a stock throughout the day), while an index fund is an investment strategy (passively tracking a market index). Most ETFs are index funds, but index funds also come in mutual fund form. When people compare “ETF vs index fund,” they are usually comparing index ETFs vs index mutual funds — both track the same indexes, produce the same returns, and have similar fees. The key practical differences are trading flexibility and how you set up automatic investments.
Which is better for beginners: ETFs or index funds?
Neither is meaningfully better — the right choice depends on your broker and account type. At Fidelity: use FZROX (0% fee index mutual fund). At Vanguard: use VTI (0.03% ETF). At Schwab: use SWTSX or SCHB (both 0.03%). In a 401(k): pick whatever S&P 500 or total market index fund has the lowest expense ratio in the plan menu. For automatic monthly contributions, index mutual funds are slightly more convenient. For taxable brokerage accounts, ETFs are slightly more tax-efficient.
Do ETFs outperform index funds?
No — ETFs and index mutual funds tracking the same index produce virtually identical returns over time. FXAIX (S&P 500 mutual fund) and VOO (S&P 500 ETF) have 10-year returns within 0.01% of each other. The fund structure does not affect performance. The expense ratio does — but both categories now offer options near 0%.
Are ETFs riskier than index funds?
No — an ETF and an index mutual fund tracking the same index hold the same stocks in the same proportions. The risk profile is identical. If the S&P 500 drops 20%, both the S&P 500 ETF and the S&P 500 mutual fund drop approximately 20%. The structure does not change the underlying risk.
Can I hold both ETFs and index mutual funds?
Yes — many investors hold both. A common setup: FZROX or FXAIX (index mutual fund) inside a Roth IRA for easy automatic contributions, and VTI or VOO (ETF) inside a taxable brokerage account for tax efficiency. There is no rule against combining them, and doing so lets you optimize for each account’s specific needs.
What expense ratio should I look for in an index fund or ETF?
Anything below 0.10% per year is excellent. The best options in 2026 are at 0.00–0.03%. As a reference point: paying 0.03% instead of 0.50% on $100,000 saves approximately $470 per year in fees — which compounds to over $30,000 over 20 years at 7% annual return. Always compare the expense ratio before buying any fund, regardless of whether it is an ETF or mutual fund.
What happens if I want to switch from an index fund to an ETF?
In a tax-advantaged account (Roth IRA, 401k), you can sell the index fund and buy the equivalent ETF with no tax consequence. In a taxable brokerage account, selling triggers a capital gains event — calculate the tax impact before switching, since the tax cost may outweigh any benefit. At Vanguard, many mutual funds can be converted directly to their ETF equivalent without triggering taxes, which is a unique Vanguard advantage.
ETF vs Index Fund: Which Is Better for a Roth IRA or 401(k)?
Inside a Roth IRA or 401(k), the ETF vs index fund decision comes down to one thing: cost. Tax efficiency is irrelevant inside a tax-advantaged account because all growth is already tax-free (Roth) or tax-deferred (traditional). This changes the calculus significantly:
- Roth IRA at Fidelity: Choose FZROX (0.00% expense ratio) — a mutual fund index fund that beats any ETF equivalent on cost alone. No need for an ETF here.
- Roth IRA at Vanguard or Schwab: VTI (Vanguard, 0.03%) or SCHB (Schwab, 0.03%) ETFs are the best options since Fidelity’s 0% funds aren’t available.
- 401(k): Almost always mutual fund index funds, not ETFs. Most 401(k) plans don’t offer ETFs. Choose the lowest-cost S&P 500 or total market index fund available.
- Taxable brokerage: ETFs win here due to superior tax efficiency. VTI or SCHB generate fewer capital gain distributions than equivalent mutual fund index funds.
ETF vs Index Fund Performance: Do the Returns Differ?
When an ETF and an index fund track the same index, their gross returns before fees are virtually identical. Both VTI (Vanguard Total Market ETF) and VTSAX (Vanguard Total Stock Market Index Fund) track the CRSP US Total Market Index. Their 10-year annualized returns as of 2025 differ by less than 0.05% — essentially the tracking error plus the expense ratio difference.
The differences in net return come entirely from fees, not from the structure itself. This is why expense ratio is the single most important variable when choosing between an ETF and an index fund tracking the same index. A 0.03% ETF and a 0.03% index fund will produce results so similar that the difference is unmeasurable over a lifetime of investing.
The 4 Questions to Ask Before Choosing ETF or Index Fund
- “What broker am I using?” If Fidelity: choose FZROX (0% mutual fund). If Vanguard, Schwab, or others: choose the equivalent ETF. The right answer depends on where your account lives.
- “Is this a tax-advantaged account?” If yes (Roth IRA, 401k): tax efficiency doesn’t matter — choose by cost. If no (taxable brokerage): ETFs have a tax efficiency advantage.
- “Do I want to invest exact dollar amounts?” If yes: choose a mutual fund index fund (accepts $1, $50, $500 — any amount). ETFs require you to buy whole shares at market price (though most brokers now offer fractional shares).
- “Will I need to sell quickly?” ETFs trade throughout the day like stocks. Mutual fund index funds process once daily at 4 PM ET. For long-term investors this is irrelevant — for active traders, ETFs offer more control.
The Verdict: ETF vs Index Fund in One Sentence
If you are investing in a Roth IRA or 401(k), use whichever index fund has the lowest expense ratio in your account — the structure does not matter. If you are investing in a taxable brokerage account, use an ETF for the tax efficiency advantage. If you are at Fidelity and want to keep it simple, use FZROX (0% fee, mutual fund) for your retirement accounts and VTI (0.03% fee, ETF) for any taxable investing. Everything else is details.
Frequently Asked Questions: ETF vs Index Fund
Is an S&P 500 ETF the same as an S&P 500 index fund?
Yes and no. Both track the S&P 500 index and produce nearly identical returns. The difference is structure: an S&P 500 ETF (like VOO or SPY) trades on an exchange throughout the day. An S&P 500 index fund (like FXAIX or VFIAX) is a mutual fund that prices once daily. Same index, same companies, different wrapper.
Are ETFs safer than index funds?
Neither is inherently safer than the other when they track the same index. “Safety” in this context is determined by what index the fund tracks — not whether it’s structured as an ETF or a mutual fund. A total market index fund and a total market ETF carry the same underlying market risk.
Can I lose all my money in an index fund or ETF?
A total market index fund or ETF would only go to zero if every publicly traded company in the US went bankrupt simultaneously — an event so extreme that money itself would have no value. In any realistic market scenario, diversified index funds recover from downturns over time. The S&P 500 has never ended a 20-year period with negative returns in its history.
Which ETF is closest to a Vanguard index fund?
VTI (Vanguard Total Stock Market ETF) is the ETF equivalent of VTSAX (Vanguard Total Stock Market Index Fund Admiral Shares). Both track the CRSP US Total Market Index and have a 0.03% expense ratio. The only differences are minimum investment ($1 for VTI vs $3,000 for VTSAX) and intraday trading capability.