Investing is one of the most powerful tools available for building long-term wealth — but for most beginners, knowing where to start is the hardest part. The good news: time does most of the heavy lifting. Using the SEC’s compound interest calculator with a hypothetical 7% average annual return, $10,000 invested once grows to about $76,000 in 30 years without adding another dollar. Real returns vary from year to year and are never guaranteed, but the lesson holds: the key is starting.
This guide covers the 7 best investment options for beginners in 2026, the right accounts to use, what to avoid, and a step-by-step action plan you can follow today — even if you’re starting from zero.
Before You Invest: 3 Things to Do First
Investing before you’re financially ready can hurt more than help. Before putting a dollar into the market:
- Build a starter emergency fund ($1,000 minimum): Without it, you’ll sell investments at the wrong moment when an unexpected expense hits. See our emergency fund guide for how to build this fast.
- Pay off high-interest debt first: Credit card debt at 20%+ APR is a guaranteed 20% return when you pay it off — better than any investment. Paying off consumer debt before investing is usually the right call.
- Have at least $50/month you can leave invested: Investing works through time and consistency, not large lump sums. $50/month at 10% average return over 30 years = over $100,000.
How Investing Works: The 4 Concepts That Matter
1. Compound interest — Your returns generate their own returns.” $1,000 at 10% becomes $1,100 after year one, then $1,210 after year two — the growth accelerates over time. This is why starting early matters more than starting with a large amount.
2. Risk and return — Higher potential returns come with higher volatility. Stocks can drop 30–40% in a recession. Bonds are more stable but grow more slowly. The right mix depends on your timeline: longer timeline = more stocks you can afford to hold through dips.
3. Diversification — Owning one stock means your fortunes are tied to one company. Owning a total market index fund means owning a small piece of thousands of companies simultaneously. If one fails, it barely moves your portfolio. Diversification is the closest thing to a free lunch in investing. See our full guide on ETF vs Index Fund: Key Differences.
4. Dollar-cost averaging — Investing the same amount every month regardless of market conditions. When markets are down, your fixed amount buys more shares. When they’re up, it buys fewer. Over time, this averages out your cost and removes the need to “time the market” — which even professional fund managers struggle to do consistently, as S&P’s SPIVA scorecards show year after year.
The 7 Best Investment Options for Beginners in 2026
1. S&P 500 Index Fund
Tracks the 500 largest US companies. The simplest, most proven investment for beginners. Fee as low as 0.015% per year (FXAIX at Fidelity). Historical average return: ~10% annually. This is the core of most beginner portfolios. If you only ever buy one investment, make it this.
2. Total Market ETF
Like the S&P 500 but broader — includes small and mid-cap US companies. Examples: VTI (Vanguard, 0.03% fee), SWTSX (Schwab, 0.03% fee). Slightly more diversified than S&P 500. Interchangeable for most beginners.
3. Roth IRA
An account type, not an investment. You put money in a Roth IRA and then invest it in index funds inside the account. The benefit: your money grows tax-free — you pay tax on contributions now, then never again on gains or qualified withdrawals. 2026 contribution limit: $7,500/year ($8,600 if 50+). Income limit: full contributions allowed under $153,000 single or $242,000 married. This is the best account for most young earners.
4. 401(k) Through Your Employer
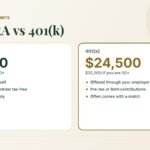
If your employer matches contributions, this is the highest-priority investment available — the match is a 100% immediate return. A 3% employer match on a $60,000 salary = $1,800 free per year. 2026 contribution limit: $24,500. Even if your fund options are limited, always contribute at least enough to get the full match.
5. Target-Date Funds
The simplest one-fund solution. Pick your target retirement year (e.g., “Vanguard Target Retirement 2055”), and the fund automatically adjusts its stock/bond mix as you age — more aggressive when you’re young, more conservative as you approach retirement. Zero decisions required. Slightly higher fees than pure index funds (typically 0.10–0.15%) but worth it for the simplicity.
6. Real Estate Investment Trusts (REITs)
Let you invest in real estate without buying property. REITs are required by law to pay out 90% of taxable income as dividends. Dividend yields are usually higher than the broader stock market, but they vary with prices and interest rates. Best for investors who want income alongside growth. Available as individual REITs or REIT ETFs (e.g., VNQ by Vanguard, 0.13% fee).
7. Robo-Advisors
Automated platforms that build and rebalance a diversified portfolio for you based on your risk tolerance. Best options: Betterment (0.25% annual fee), Wealthfront (0.25%). Good for beginners who want a fully managed approach. Slightly higher cost than DIY index funds but much lower than a traditional financial advisor (typically 1%+).
Best Investments for Beginners: Full 2026 Comparison
| Investment | Annual Fee | Risk Level | Best Account | Minimum to Start |
|---|---|---|---|---|
| S&P 500 Index Fund (FXAIX) | 0.015% | Medium | Roth IRA / 401k | $1 |
| Total Market ETF (VTI) | 0.03% | Medium | Roth IRA / Taxable | $1 (fractional) |
| Roth IRA (account) | Varies by fund | Varies | — | $0 to open |
| 401k | Varies by plan | Varies | — | $0 (via payroll) |
| Target-Date Fund | 0.10–0.15% | Medium-Low | Roth IRA / 401k | $1,000 (some) |
| REIT ETF (VNQ) | 0.12% | Medium | Roth IRA | $1 (fractional) |
| Robo-Advisor | 0.25%/year | Varies | Any | $0–$500 |
401k vs Roth IRA: Which Account Should You Use First?
This is the most important question for beginner investors — and the one most guides skip. Here’s the answer:
Step 1: Contribute to your 401k up to the employer match.
If your employer matches 3% of your salary, contribute at least 3%. The match is a 100% immediate return — nothing else comes close. Skipping the match is leaving free money on the table.
Step 2: Max out your Roth IRA ($7,500 in 2026).
After getting the full 401k match, switch to your Roth IRA. Your money grows tax-free for decades — the compounding benefit of tax-free growth over 30 years is enormous. A 25-year-old who maxes their Roth IRA every year until 65 at 7% average return ends up with over $1.4 million — all tax-free.
Step 3: Return to your 401k.
Once the Roth IRA is maxed, go back to your 401k and contribute more, up to the $24,500 limit. Even if your 401k fund options are mediocre, the tax deferral on contributions is still valuable.
Step 4: Open a taxable brokerage account.
After maxing tax-advantaged accounts, invest additional money in a standard brokerage account (Fidelity, Schwab, Vanguard). No contribution limits, no tax advantages, but full flexibility.
Best Brokerages for Beginners in 2026
| Broker | Account Minimum | Fractional Shares? | Best For | Key Feature |
|---|---|---|---|---|
| Fidelity | $0 | ✅ Yes (from $1) | Best overall for beginners | FZROX: 0% expense ratio index fund |
| Charles Schwab | $0 | ✅ Yes (from $5) | Great research tools | SWTSX: 0.03% expense ratio |
| Vanguard | $0 | ✅ Yes | Index fund purists | Invented the index fund; lowest average fund costs |
| Betterment | $0 | ✅ Automated | Hands-off investors | Automated rebalancing, tax-loss harvesting |
Recommendation for most beginners: Open a Roth IRA at Fidelity. It takes 10 minutes. Fund it with FXAIX (S&P 500 index fund, 0.015% fee). Set up a monthly automatic contribution. Done.
How to Start Investing: Step-by-Step Action Plan
Step 1 — Build your $1,000 emergency fund first.
Don’t skip this. If you invest before you have a cash cushion, you’ll be forced to sell investments at the wrong time when life happens.
Step 2 — Contribute to your 401k at work, at minimum up to the employer match.
Log into your HR portal this week. Set your 401k contribution percentage to at least the employer match. This is non-negotiable free money.
Step 3 — Open a Roth IRA.
Go to Fidelity.com, Schwab.com, or Vanguard.com. Open a Roth IRA (it’s free and takes 10 minutes). Link your bank account and make your first contribution.
Step 4 — Choose your investment.
For 95% of beginners, the right answer is an S&P 500 index fund or total market index fund. Pick one: FXAIX (Fidelity), SWTSX (Schwab), or VTI (Vanguard). Don’t overthink this step.
Step 5 — Set up automatic monthly contributions.
Schedule a recurring transfer on payday. Even $50/month is a start. Automation is what separates people who actually build wealth from those who always plan to start “next month.”
Step 6 — Don’t touch it.
The biggest mistake beginners make is selling when markets drop. Markets always recover — but only if you stay invested. Set it, automate it, and ignore the daily news.
Common Beginner Investing Mistakes to Avoid
- Waiting for the “right time” to invest. There is no right time. Time in the market beats timing the market — consistently, over every period studied. Every year you wait costs you roughly 10% average compounding.
- Picking individual stocks. Over 90% of actively managed funds underperform their index benchmark over 15+ years (SEC data). Individual stock picking is harder than it looks and rarely beats diversified index funds long-term.
- Ignoring fees. A 1% annual fee sounds trivial but costs approximately $78,000 on a $100,000 portfolio over 30 years compared to a 0.03% fee. Fees compound against you just like returns compound for you.
- Selling during market crashes. Market downturns feel catastrophic in the moment. The S&P 500 has recovered from every crash in history — including 2008, 2020, and 2022. Selling locks in your losses.
- Skipping the 401k employer match. This is the highest guaranteed return available anywhere. If your employer matches 50 cents per dollar up to 6% of your salary, skipping it means leaving a 3% salary bonus on the table every year.
- Investing before paying off high-interest debt. Investing at 7–10% average returns while carrying credit card debt at 20%+ APR is a losing trade. Pay the high-interest debt first.
How Much to Invest: A Simple Framework by Income
| Monthly Take-Home | 20% Investment Goal | After 10 Years (7% avg) | After 20 Years (7% avg) |
|---|---|---|---|
| $2,500 | $500/month | ~$87,000 | ~$261,000 |
| $3,500 | $700/month | ~$122,000 | ~$365,000 |
| $5,000 | $1,000/month | ~$174,000 | ~$521,000 |
| $7,500 | $1,500/month | ~$261,000 | ~$782,000 |
Use our Compound Interest Calculator to model exactly what your monthly investment contributions will grow to at different return rates. The numbers are consistently surprising — even small amounts invested consistently become significant wealth over time.
Frequently Asked Questions About Investing for Beginners
What is investing and why should I start?
Investing is putting your money to work so it grows over time. Unlike a savings account, investing in assets like stocks or index funds has historically delivered much higher returns over the long term. The sooner you start, the more time your money has to grow through compound interest.
How much money do I need to start investing?
Less than you think. Many platforms allow you to start with as little as $1 or $10 through fractional shares. The amount matters less than starting — consistency over time is what builds real wealth.
What should a beginner invest in first?
For most beginners, a low-cost index fund or ETF tracking the S&P 500 is the best starting point. It gives you instant diversification across hundreds of companies without requiring you to pick individual stocks.
Is investing risky for beginners?
All investing carries some risk, but diversified index funds spread that risk across many companies. The biggest risk for most beginners isn’t market volatility — it’s not starting at all and missing years of potential growth.
Should I pay off debt before investing?
If you have high-interest debt above 6-7%, pay that off first. For low-interest debt, you can do both simultaneously. Always have a small emergency fund before you start investing.
How do I actually start investing?
Open a brokerage account — Fidelity, Schwab, or Vanguard are popular beginner-friendly options in the US. Choose a low-cost index fund, set up automatic monthly contributions, and leave it alone. That’s it.
💡 Want to see your numbers? Try our free Compound Interest Calculator — enter your monthly investment and interest rate to see how much you could build over time.
Frequently Asked Questions About Investing for Beginners
How much money do I need to start investing?
You can start with as little as $1 using fractional shares on platforms like Fidelity or Charles Schwab. Most S&P 500 index funds and ETFs require no minimum when purchased through a major brokerage. The key is starting — time in the market matters far more than the amount you start with. $50/month invested consistently from age 25 grows to over $260,000 by age 65 at 7% average returns.
What’s the best investment for a complete beginner?
An S&P 500 index fund (like FXAIX or VOO) inside a Roth IRA. You get instant diversification across 500 of the largest US companies, ultra-low fees (as low as 0.015%), and tax-free growth. If you want something even simpler, a target-date fund requires zero ongoing decisions — just pick your retirement year and let it run.
Is investing safe for beginners?
All investing involves risk — the value of investments can go down as well as up. However, long-term investing in diversified index funds has historically been one of the safest ways to grow wealth. The S&P 500 has never failed to recover and reach new highs after every crash in history. The key risk reducer for beginners is diversification (owning many assets, not just one) and time horizon (don’t invest money you’ll need within 5 years).
What’s the difference between a 401k and a Roth IRA?
A 401k is offered through your employer — contributions are pre-tax (you pay tax when you withdraw in retirement). A Roth IRA is opened independently — contributions are post-tax, but growth and withdrawals are completely tax-free. Most beginners benefit more from a Roth IRA, especially if they expect to be in a higher tax bracket later. The 2026 limits are $24,500 for a 401(k) and $7,500 for a Roth IRA. For a deeper dive, read our Roth IRA for Beginners: The Complete 2026 Guide.
Should I invest or pay off debt first?
It depends on the interest rate. For high-interest debt (credit cards at 15%+): pay it off first — a guaranteed 20% return beats any investment. For low-interest debt (student loans under 5%, mortgages): invest and pay the debt simultaneously. One exception: always contribute to your 401k at least up to the employer match, even if you have debt — the match is a 100% immediate return that outweighs almost any debt cost.
What is dollar-cost averaging?
Investing a fixed amount at regular intervals (e.g., $200 every month) regardless of market conditions. When markets are down, your $200 buys more shares. When markets are up, it buys fewer. Over time, this averages out your purchase price and removes the temptation to time the market. It’s the approach most financial advisors recommend for beginners, and it’s what automatic investing does by default.
How long does it take to see returns from investing?
Investing is a long-term process — typically 10, 20, or 30+ years. In the short term (1–3 years), markets are volatile and your portfolio may lose value. Over 10+ years, diversified index fund portfolios have historically been positive in almost every scenario. The longer your timeline, the more predictable and reliable the outcomes become. Don’t invest money you’ll need within the next 3–5 years.