There’s no single “right” amount to save each month — it depends on your income, your goals, and where you are financially right now. But there are clear benchmarks that make a real difference. BLS Consumer Expenditure data shows the average American saves less than 5% of their income — well below the 20% most financial financial planners widely recommend. This guide helps you figure out your number and actually hit it. Related: saving for a home down payment.
The honest answer is that there’s no single magic number that works for everyone. But there are well-established guidelines, practical frameworks, and age-specific benchmarks that can help you figure out what’s right for your situation — and whether you’re on track.
Why Saving a Specific Amount Matters
Before we get into the numbers, it’s worth understanding why having a specific savings target matters so much more than just “saving what’s left over.”
Saving what’s left over almost never works. By the time you’ve paid your bills, bought groceries, filled your car with fuel, and spent a little on leisure, there’s usually very little — if anything — left. And if there is something left, it tends to disappear into small, unmemorable purchases.
Having a specific monthly savings target changes the dynamic completely. Instead of saving what’s left, you save first and spend what’s left. This simple reversal — known as paying yourself first — is one of the most powerful habits in personal finance.
The Standard Rule: Save 20% of Your Take-Home Pay
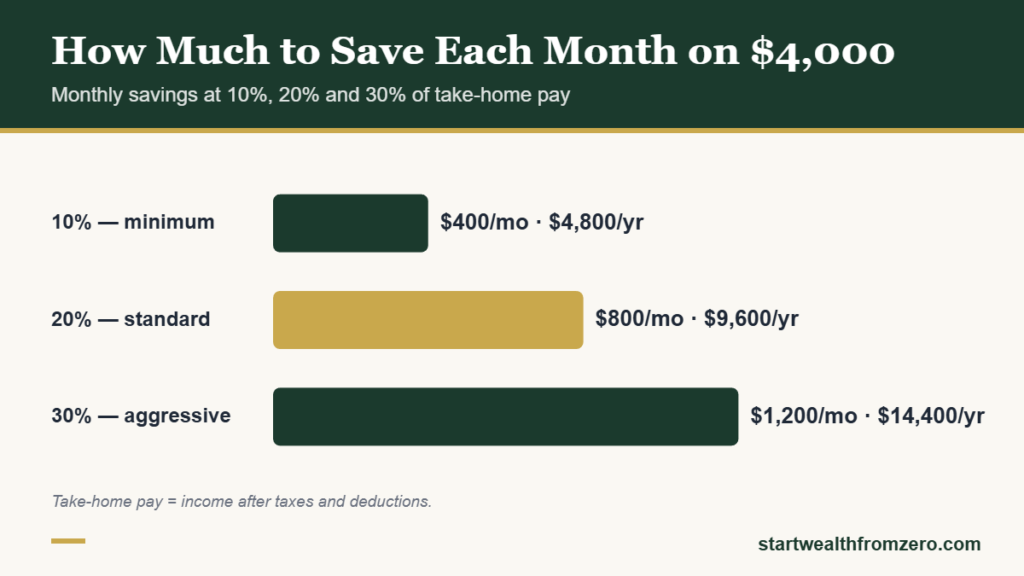
The most widely cited savings benchmark is 20% of your take-home pay, as outlined in the 50/30/20 budgeting rule. Under this framework, 50% of your income goes to needs, 30% to wants, and 20% to savings and debt repayment.
Here’s what 10%, 20% and 30%+ of take-home pay looks like at different income levels:
| Monthly Income | Minimum (10%) | Recommended (20%) | Aggressive (30%+) |
|---|---|---|---|
| $2,000 | $200 | $400 | $600 |
| $3,000 | $300 | $600 | $900 |
| $4,000 | $400 | $800 | $1,200 |
| $5,000 | $500 | $1,000 | $1,500 |
| $7,500 | $750 | $1,500 | $2,250 |
| $10,000 | $1,000 | $2,000 | $3,000+ |
If 20% feels unachievable right now, that’s okay. Start with whatever you can — even 5% is better than nothing — and increase it gradually over time as your income grows or your expenses reduce.
How Much Should You Save by Age?
Age is an important factor in savings because of the power of compound interest. The earlier you start, the less you need to save each month to reach the same outcome. Here’s a general breakdown of savings benchmarks by age:
In Your 20s
Your 20s are arguably the most important decade for saving, even though your income is likely at its lowest. This is because money saved and invested in your 20s has the longest time to compound.
The general recommendation for your 20s is to save at least 10-20% of your income and focus on three things in this order:
- Build a starter emergency fund of $1,000
- Pay off any high-interest debt
- Start contributing to a retirement account, even if only a small amount
If you’re in your early 20s and just starting out, don’t be discouraged if you can only save $50-100 per month. The habit is more important than the amount at this stage.
In Your 30s
By your 30s, your income is likely higher but your expenses may also be greater — a mortgage or higher rent, possibly a family, car payments, and so on. The recommendation for this decade is to save 15-20% of your income and to have built up:
- A fully funded emergency fund of 3-6 months of expenses
- A growing retirement fund
- Progress toward any medium-term goals like a home deposit
In Your 40s
Your 40s are often peak earning years, which makes them crucial for building wealth. If you haven’t saved aggressively in your 20s and 30s, this is the decade to make up for lost time. Aim to save 20-25% of your income and focus heavily on retirement contributions.
In Your 50s and Beyond
With retirement approaching, the focus shifts to maximizing contributions and reducing debt. Aim to save 25-30% of your income if possible, take advantage of any catch-up contribution allowances in retirement accounts, and begin thinking about how to make your savings last.
As a rough guide, many people aim to raise their savings rate as their income grows. These targets are suggestions, not rules:
| Age | Savings Target (% of income) | Minimum Monthly (on $3,000 take-home) | Stretch Goal |
|---|---|---|---|
| 20s | 15–20% | $450–$600 | 25%+ (compound interest is most powerful here) |
| 30s | 20–25% | $600–$750 | 30% (catch up if 20s were slow) |
| 40s | 25–30% | $750–$900 | 35% (peak earning years) |
| 50s | 30–40% | $900–$1,200 | Max out retirement contributions |
If you’re behind on savings, don’t panic — start with 10% and increase by 1–2% every 6 months. Use our Savings Calculator to see how quickly consistent saving adds up, and our Net Worth Calculator to track your overall financial progress.
Retirement Savings Benchmarks by Age
| Age | Retirement Savings Goal (Fidelity guideline) | What This Means |
|---|---|---|
| 30 | 1× your annual salary | $40,000 if you earn $40k/year |
| 35 | 2× your annual salary | $100,000 if you earn $50k/year |
| 40 | 3× your annual salary | $180,000 if you earn $60k/year |
| 50 | 6× your annual salary | $420,000 if you earn $70k/year |
| 60 | 8× your annual salary | $640,000 if you earn $80k/year |
| 67 | 10× your annual salary | $900,000 if you earn $90k/year |
Use our free Savings Calculator to see exactly how long it will take to hit your target at your current monthly savings rate.
How to Figure Out Your Personal Savings Target
Rather than just following a general rule, here’s a simple process to work out your own monthly savings target:
Step 1: Calculate your take-home pay. Start with what actually lands in your bank account each month after tax and other deductions.
Step 2: List your essential expenses. Rent, bills, groceries, transport, minimum debt payments. Add these up.
Step 3: Subtract essentials from take-home pay. What’s left is your discretionary income — the money you have control over.
Step 4: Decide what percentage to save. Aim for 20% of take-home pay as a target. If your discretionary income is less than 20% of your take-home pay, you need to either reduce expenses or increase income.
Step 5: Set up an automatic transfer. Whatever amount you decide to save, automate it. Set up a transfer to a savings account on payday so the money moves before you have a chance to spend it.
What Should You Be Saving For?
Knowing how much to save is only half the picture. Equally important is knowing what you’re saving for, because different goals require different strategies.
Emergency Fund
This should be your first savings priority, before anything else. Aim for 3-6 months of essential expenses in a readily accessible account. Until this is in place, every unexpected expense is a potential financial crisis.
Retirement
Time is your biggest asset when it comes to retirement savings. The earlier you start, the less you need to contribute each month to reach a comfortable retirement. If your employer offers a 401(k) match, contribute at least enough to get the full match — it’s essentially free money.
Short and Medium-Term Goals
A home down payment, a car, a vacation, a wedding — whatever your medium-term goals are, they need their own dedicated savings pot. Mixing these savings with your emergency fund or everyday account makes it too easy to spend them.
Wealth Building
Once your emergency fund is in place and you’re contributing to retirement, any additional savings capacity can go toward building long-term wealth through investing in low-cost index funds.
What If You Can’t Save 20%?
If 20% feels impossible given your current income and expenses, here’s the most important thing to remember: saving something is infinitely better than saving nothing.
Start with 1% if that’s all you can manage. Then increase it by 1% every month or every time you get a raise. Over time, these small incremental increases add up to a meaningful savings rate without requiring any dramatic lifestyle changes.
The goal is to build the habit first and increase the amount over time. A person who consistently saves 5% of their income for 10 years will almost always end up in a better financial position than someone who saves nothing for 9 years and then tries to save 30% in year 10.
The Bottom Line
How much should you save each month? As a starting point, aim for 20% of your take-home pay. If you’re in your 20s, focus on building the habit even if the amount is small. If you’re in your 30s or 40s, increase your savings rate as your income grows. And regardless of your age or income, automate your savings so it happens without requiring willpower every month.
The best savings rate is the one you can sustain consistently. Start where you are, increase gradually, and let time and compound interest do the heavy lifting.
Not sure where to put your savings? A high-yield savings account earning around 4% APY is the best place to park money you’ll need within 1–3 years. For longer-term savings, consider investing in index funds.
Frequently Asked Questions
How much should I save each month as a percentage of my income?
The standard recommendation is to save at least 20% of your take-home pay, as suggested by the 50/30/20 rule. However, even saving 5-10% consistently is a strong start if you’re on a tight income. The percentage matters less than the habit — start with whatever you can and increase it over time.
How much should I have saved by age 30?
Fidelity’s widely used guideline is to have about one year’s salary saved for retirement by age 30 — so about $40,000 if you earn $40,000 a year. Your emergency fund and other savings goals come on top of that.
Does my savings rate matter more than how much I earn?
Yes, significantly. Someone earning $50,000 and saving 30% will build more wealth than someone earning $100,000 and saving 5%. Your savings rate — the gap between what you earn and what you spend — is the most powerful factor in building long-term wealth.
Where should I put my monthly savings?
Follow this priority order: first, a high-yield savings account for your emergency fund. Then maximize any employer 401k match — that’s free money. Then a Roth IRA if you’re eligible. Then a taxable brokerage account for additional investing. Each step builds on the last.
How much should a 25-year-old save per month?
At 25, a common guideline is to save at least 15-20% of your take-home pay. If that’s not possible yet, start with 5-10% and increase by 1% each year. Time is your biggest asset at 25 — even small amounts compound significantly over 40 years.
What if I can only save $50 or $100 per month?
That’s a perfectly valid starting point. $100/month invested at 7% average returns grows to roughly $265,000 over 40 years. The habit matters more than the amount when you’re starting out.
Should I save for an emergency fund or invest first?
Emergency fund first — always. Build 3-6 months of expenses in a high-yield savings account before investing. This prevents you from having to sell investments at a loss during a crisis.
How much should I save if I have debt?
Save at least enough to get any employer 401(k) match (that’s free money), then aggressively pay off high-interest debt (above 7% APR), then return to investing. Low-interest debt (below 5%) can be paid off more gradually alongside saving.
Related resources: save for a car.
Disclaimer: This article is for informational purposes only and does not constitute financial advice.