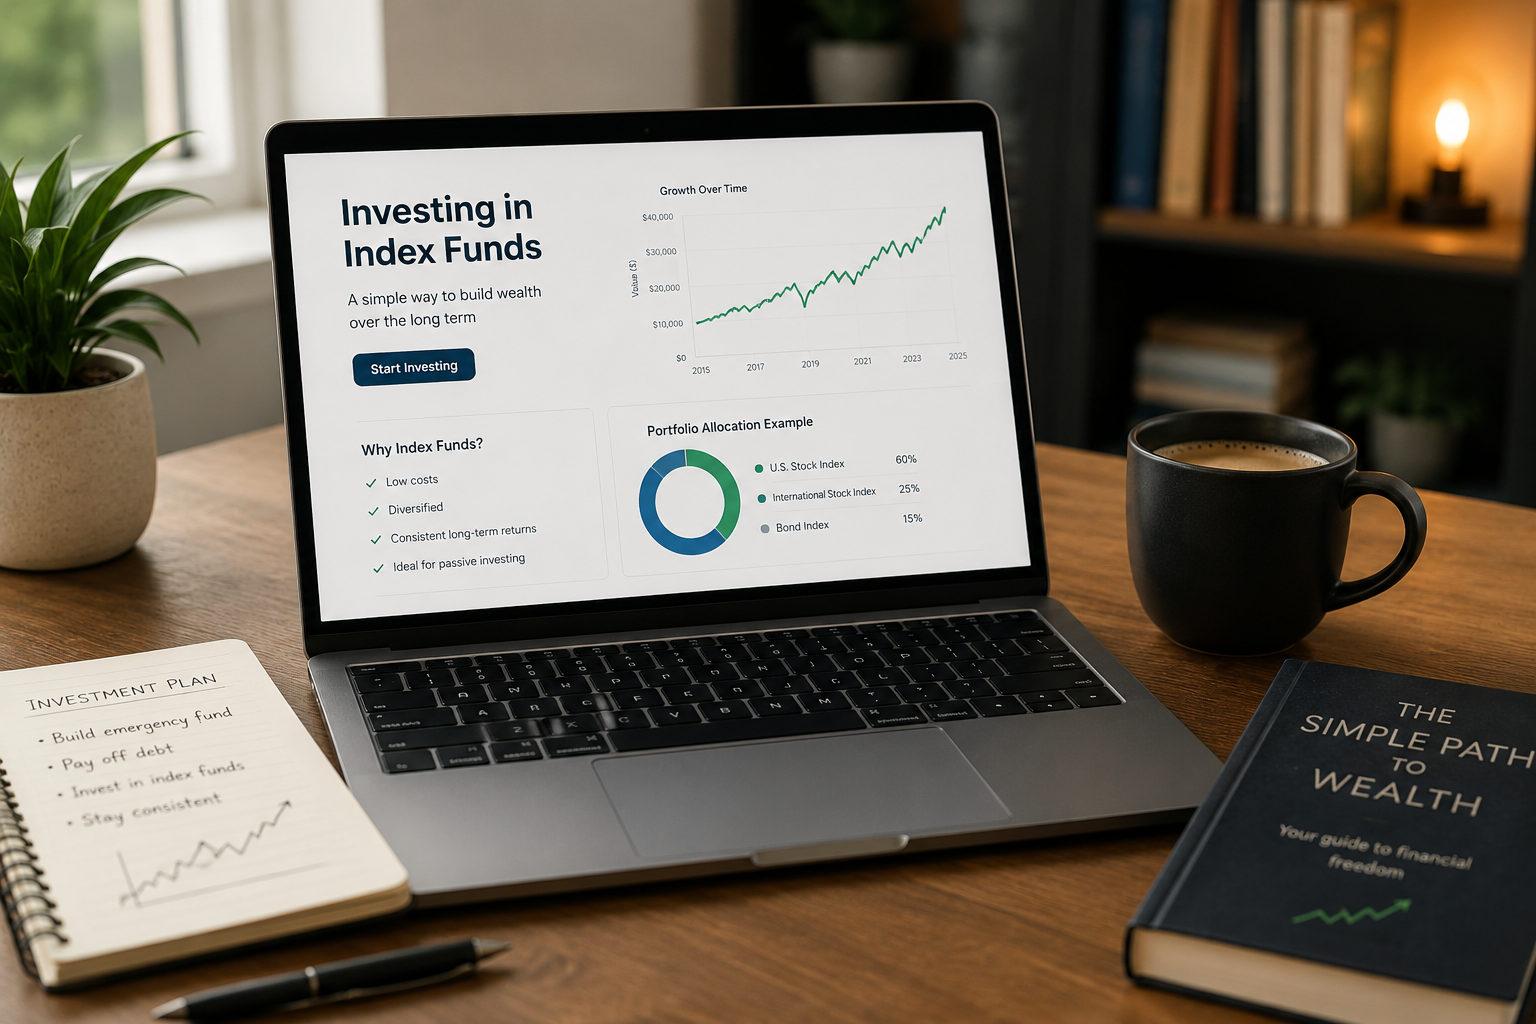
Index funds are how many ordinary people build long-term wealth — not by picking stocks or timing the market, but by owning a small piece of hundreds or thousands of companies at once. Because an index fund simply tracks a market index, it usually costs far less to run than an actively managed fund, and as the SEC’s Investor.gov explains, those costs come out of your returns every year.
Low costs are a big part of why index funds work: S&P’s SPIVA scorecards show that, after fees, most actively managed U.S. stock funds have trailed their benchmark index over long periods. Some broad-market index funds now charge less than 0.05% a year.
Yet despite its simplicity and proven track record, many people never start investing in index funds because the process feels unfamiliar and the terminology confusing. This guide removes that barrier completely, walking you through exactly what index funds are, why they work, and how to make your first investment — step by step.
How to Start Investing in Index Funds: Step by Step
Here’s the whole process from zero to your first automatic investment. Most people can finish steps 2–5 in under an hour.
Step 1: Build your financial foundation first
Before investing in index funds, ensure you have:
- An emergency fund of 3-6 months of expenses (use our Emergency Fund Calculator to set your target)
- No high-interest debt (credit cards, personal loans above 7-8% interest)
- A stable monthly income with consistent surplus after essential expenses
Investing money you might urgently need — or while carrying high-interest debt — undermines the benefits of long-term index fund investing.
Step 2: Choose your investment account
The account you invest through matters as much as what you invest in, because of the significant tax advantages available through certain account types.
In the United States:
- Roth IRA: Contribute after-tax money, all future growth and withdrawals are completely tax-free. Annual contribution limit of $7,500 in 2026 (under 50). Ideal for most beginners.
- Traditional IRA: Contributions may be tax-deductible, growth is tax-deferred, withdrawals in retirement are taxed as income.
- 401(k): Employer-sponsored retirement account with higher contribution limits. Always contribute at least enough to get the full employer match — it’s free money.
- Traditional 401(k) or IRA: Contributions can lower your taxable income today, and you pay income tax when you withdraw the money in retirement.
Step 3: Choose your investment platform
Once you’ve decided on your account type, choose a platform to open it through. Key factors to consider:
- Fees: Look for platforms with low or no account fees and low dealing charges
- Fund availability: Ensure your chosen platform offers the index funds you want to invest in
- User experience: A clear, easy-to-use interface makes investing regularly more straightforward
- Reputation and regulation: Only use regulated, established platforms
Popular platforms in the US include Vanguard, Fidelity, Charles Schwab, and for beginners, robo-advisors like Betterment and Wealthfront.
Step 4: Make your first investment
Once your account is open and funded, search for your chosen index fund by name or ticker symbol. Enter the amount you want to invest and confirm the transaction.
Your first index fund investment might feel anticlimactic — a few clicks, a confirmation email, and that’s it. But that simplicity is precisely the point. Index fund investing should be boring. The work is in starting and staying consistent, not in making complex decisions.
Step 5: Set up automatic monthly contributions
The most powerful habit in index fund investing is investing a fixed amount every month, regardless of what the market is doing. This strategy — called dollar-cost averaging — means you automatically buy more shares when prices are low and fewer when prices are high, reducing your average cost per share over time.
Set up an automatic monthly transfer from your bank account to your investment account, timed for the day after payday. Even $50-100 per month, invested consistently over decades, compounds into a substantial sum.
How to Choose Your First Index Fund
For most beginners, the decision comes down to two options:
Option 1: An S&P 500 index fund
Tracks the 500 largest US companies. Historically strong returns, extremely low costs, and the most widely recommended starting point for most investors. Examples include Vanguard’s VOO, iShares’ IVV, and Fidelity’s FXAIX.
Option 2: A total world stock market fund
Tracks thousands of companies across both developed and emerging markets worldwide. Provides broader geographic diversification than an S&P 500 fund. Examples include Vanguard’s VT and iShares’ MSCI World ETF.
Both are excellent choices. The S&P 500 has outperformed global funds historically, but past performance doesn’t guarantee future results. Many financial advisors recommend holding both — a majority in a US index fund and a minority in an international fund — for balanced diversification.
As we explored in our detailed comparison of index funds vs ETFs, both investment vehicles offer similar exposure and low costs, with minor differences in trading flexibility and minimum investment amounts.
What Is an Index Fund?
An index fund is a type of investment fund that tracks a specific market index — a list of companies grouped by certain criteria. The most famous example is the S&P 500, which tracks the 500 largest publicly traded companies in the United States, including Apple, Microsoft, Amazon, Google, and Berkshire Hathaway.
Instead of a fund manager actively picking stocks in an attempt to beat the market, an index fund simply buys all the stocks in the index it tracks, in the same proportions. When you invest in an S&P 500 index fund, you effectively own a tiny piece of all 500 companies simultaneously.
This passive approach has two significant advantages over active fund management: lower costs (because no expensive research or trading is required) and, historically, better long-term performance (because most active fund managers fail to beat their benchmark index after fees over long periods).
According to S&P Dow Jones Indices, over 90% of actively managed US large-cap funds underperformed the S&P 500 over a 20-year period. This is the fundamental case for index fund investing.
Index funds come as mutual funds or ETFs — both work for the steps above. If you’re unsure which to pick, see our ETF vs index fund comparison.
Why Index Funds Are Ideal for Beginners
Index funds have several characteristics that make them particularly well-suited to beginner investors:
Instant diversification. A single S&P 500 index fund gives you exposure to 500 different companies across multiple sectors. This diversification means that even if several companies perform poorly, the overall impact on your investment is limited.
Low costs. Index funds charge extremely low annual fees — known as expense ratios — because they require minimal management. The best index funds charge as little as 0.03% per year. On a $10,000 investment, that’s just $3 per year in fees — compared to 1-2% per year for actively managed funds.
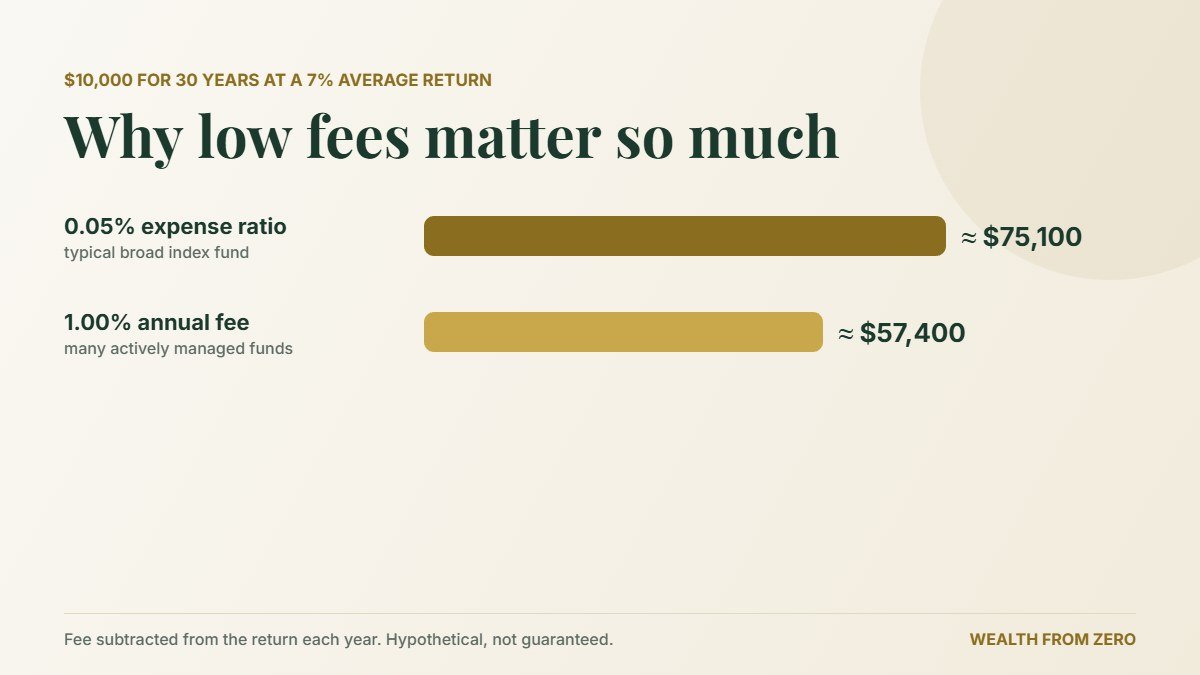
The cost advantage is significant: According to Investor.gov (SEC), actively managed funds charge an average of 0.5–1% per year in fees, while index funds often charge 0.03–0.20%. Over 30 years on a $10,000 investment, that difference alone can cost you tens of thousands of dollars.
No expertise required. You don’t need to research individual companies, analyze financial statements, or predict market movements. You simply invest regularly and let the market do the work.
Proven long-term performance. The S&P 500 has delivered an average annual return of approximately 10% before inflation over the past century — including multiple recessions, financial crises, and market crashes. Patient, long-term index fund investors have historically been rewarded.
Types of Index Funds
Not all index funds track the same index. Here are the main types you’ll encounter:
Broad Market Index Funds
These track the entire stock market of a country or region. Examples include funds tracking the total US stock market (all publicly traded US companies), or a global index covering thousands of companies worldwide. Broad market funds provide the widest possible diversification.
Large-Cap Index Funds
These track indices of the largest companies in a market — like the S&P 500 in the US. Large-cap funds are the most popular starting point for beginner investors due to their strong historical performance and the familiarity of the companies they contain.
International Index Funds
These track stock markets outside your home country — European markets, emerging markets like China and India, or a global index excluding your home country. International funds provide geographic diversification that reduces your dependence on any single economy.
Bond Index Funds
These track indices of bonds — debt instruments issued by governments or companies. Bond index funds are generally lower risk than equity index funds but also offer lower long-term returns. They’re most useful as a stabilizing component of a diversified portfolio, particularly for investors closer to retirement.
Sector Index Funds
These track specific sectors of the economy — technology, healthcare, real estate, energy, and so on. Sector funds are more concentrated and therefore riskier than broad market funds. They’re generally not recommended as a starting point for beginners.
How Index Funds Work: A Simple Example
Imagine you invest $1,000 in an S&P 500 index fund. Your $1,000 is immediately spread across all 500 companies in the index, proportionally to their size. Apple (one of the largest companies) might represent about 7% of your investment ($70), while a smaller company might represent 0.1% ($1).
As these companies grow and generate profits, the value of your index fund rises. Dividends paid by companies in the index are typically reinvested automatically, buying you more shares of the fund — compounding your returns over time.
When one company grows significantly, its weighting in the index increases and your fund automatically holds more of it. When a company shrinks or is removed from the index, your exposure decreases automatically. You never need to make any decisions — the fund manages itself.
The Power of Compound Growth in Index Funds
The real magic of index fund investing comes from compound growth over long periods. Consider the following examples based on a 8% average annual return (slightly below the S&P 500’s historical average to be conservative):
| Monthly Investment | After 10 Years | After 20 Years | After 30 Years |
|---|---|---|---|
| $100/month | $18,295 | $58,902 | $149,036 |
| $200/month | $36,590 | $117,804 | $298,072 |
| $500/month | $91,473 | $294,510 | $745,180 |
| $1,000/month | $182,946 | $589,020 | $1,490,359 |
These figures assume all dividends are reinvested and no money is withdrawn. The dramatic difference between 10, 20, and 30 years illustrates why starting early is the single most important factor in index fund investing — time does most of the heavy lifting.
Use our Compound Interest Calculator to model your own investment scenario with your specific monthly contribution and time horizon.
Common Mistakes Beginner Index Fund Investors Make
Trying to time the market. Many beginners wait for the “right time” to invest — when prices are lower, when the economy looks better, when they feel more confident. This is a mistake. Time in the market consistently beats timing the market. The best time to invest is always now.
Checking the portfolio too frequently. Daily portfolio checking leads to emotional reactions to normal market fluctuations. Index fund investing works over years and decades — checking weekly or monthly is more than sufficient, and quarterly is ideal.
Panic selling during downturns. Market corrections and crashes are normal, temporary, and — for long-term investors — buying opportunities. Selling during a downturn locks in losses and means missing the recovery. The investors who earn the best long-term returns are those who stay invested through volatility.
Choosing funds with high expense ratios. Even small differences in fees compound significantly over time. A fund charging 1% per year costs dramatically more than one charging 0.05% over a 30-year investment period. Always check the expense ratio before investing.
Not reinvesting dividends. Ensure your investment account is set to automatically reinvest dividends. Dividend reinvestment compounds your returns significantly over long periods.
What to Expect in the First Year
Your first year of index fund investing will likely feel underwhelming. Markets may rise or fall. Your portfolio might be worth less than you invested at some point. Progress will feel slow when your contributions are small relative to your balance.
This is completely normal. Index fund investing is a long-term game measured in decades, not months. The first year is about building the habit — investing consistently, not reacting to short-term movements, and letting compound growth begin its work.
Here’s a realistic picture of what $200/month invested in an S&P 500 index fund might look like:
| Year | Total Contributed | Estimated Portfolio Value (8% return) |
|---|---|---|
| Year 1 | $2,400 | $2,490 |
| Year 3 | $7,200 | $8,093 |
| Year 5 | $12,000 | $14,694 |
| Year 10 | $24,000 | $36,590 |
| Year 20 | $48,000 | $117,804 |
| Year 30 | $72,000 | $298,072 |
The numbers in the early years are modest. But by year 20 and beyond, compound growth has done extraordinary work — turning $48,000 of contributions into $117,804, and $72,000 into nearly $300,000.
Frequently Asked Questions
Below are the most common questions people ask about how to invest in index funds for beginners — answered simply and clearly.
How much money do I need to start investing in index funds?
Many platforms allow you to start with as little as $1 through fractional shares. A more practical starting point is $50-100 to make the investment feel meaningful. The amount matters less than starting consistently.
Are index funds safe?
Index funds are subject to market risk — their value falls when markets fall. They are not “safe” in the way a savings account is safe. However, broadly diversified index funds have never permanently lost value over long periods historically. The risk is short-term volatility, not permanent loss for patient investors.
How long should I hold index funds?
Index funds are long-term investments. A minimum time horizon of 5 years is generally recommended, with 10-20+ years ideal to fully benefit from compound growth and to smooth out market volatility.
Should I invest a lump sum or monthly contributions?
Research suggests that lump sum investing (investing all available money immediately) slightly outperforms monthly contributions on average, because money is invested and compounding sooner. However, monthly contributions (dollar-cost averaging) reduce the risk of investing a large sum just before a market downturn and are more psychologically manageable for most people. Either approach is significantly better than not investing at all.
Can I lose all my money in an index fund?
For a broad market index fund to go to zero, every company in the index would need to become worthless simultaneously — an effectively impossible scenario in a functioning economy. While significant losses are possible during severe market downturns, permanent total loss of a diversified index fund investment has never occurred historically.
Related resources: compound interest calculator, investing for beginners.
Related resources: invest money wisely.
Disclaimer: This article is for informational purposes only and does not constitute financial advice.