Getting your first paycheck is one of those moments you don’t forget. After weeks of showing up, working hard, and waiting, your account suddenly has more money in it than it ever has before. It feels great. And then — almost immediately — the question hits: what do I actually do with this?
Below are the steps to take with your first paycheck, in the order that matters most.
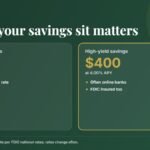
High-yield savings accounts were paying around 4.0–4.2% APY in September 2026 (Bankrate) — roughly ten times the 0.38% national average (FDIC) for standard savings accounts.
For most 18-year-olds, nobody has ever sat down and explained what to do with money when it arrives. School teaches algebra and history, but almost nothing about how to manage the income you’ll spend your entire adult life earning. The result is that most young people either spend their first paycheck almost immediately on things they barely remember a month later, or they leave it sitting in a checking account with no plan whatsoever.
Neither approach sets you up well. But the good news is that the right approach isn’t complicated — and getting it right from the very beginning puts you years ahead of your peers financially.
This guide will walk you through exactly what to do with your first paycheck at 18, step by step.
Why Your First Paycheck Matters More Than You Think
| Your First Paycheck: Where Should It Go? | % to Allocate | Why |
|---|---|---|
| Essential bills (rent, food, transport) | 50% | Non-negotiable — keep the lights on |
| Emergency fund savings | 20% | Build this before anything else |
| Wants / lifestyle | 20% | You earned it — enjoy some |
| Investing / extra savings | 10% | Start the habit early, even small |
Your first paycheck isn’t just money. It’s the beginning of a financial habit. Whatever you do with your first paycheck tends to set a pattern — consciously or unconsciously — for how you handle money going forward.
People who spend their first paycheck impulsively tend to develop a spend-first mindset that follows them for years. People who immediately put a portion away before spending anything else tend to develop a save-first mindset that becomes a lifelong habit.
The habits you form around money at 18 are genuinely difficult to break later. Getting them right from the start — or at least heading in the right direction — is one of the best investments you can make in your future self.
There’s also the mathematical reality of compound interest. Money saved and invested at 18 has more time to grow than money saved at any other point in your life. Even small amounts set aside consistently in your late teens and early 20s can be worth dramatically more by the time you reach retirement than much larger amounts saved later.
Step 1: Don’t Spend It All Immediately
This sounds obvious, but it needs to be said. The temptation to celebrate your first paycheck with a big purchase — new clothes, a night out, the latest gadget — is real and completely understandable. You earned it, after all.
There’s nothing wrong with spending some of your first paycheck on something enjoyable. But spending all of it, or most of it, on immediate consumption sets a pattern that’s hard to break and expensive to maintain.
Before you spend a single penny of your first paycheck, decide what percentage you’re going to save. Commit to that number. Then — and only then — spend the rest however you like.
Step 2: Open a Separate Savings Account
If you don’t already have one, open a dedicated savings account separate from your everyday checking account. This is important for two reasons.
First, money in a separate account is psychologically harder to spend. When your savings are mixed in with your everyday spending money, the temptation to dip into them is much higher. Out of sight genuinely does mean out of mind.
Second, a savings account earns interest on your balance. Even a modest interest rate means your savings are growing slightly just by sitting there. Look for a high-yield savings account that offers the best available interest rate while keeping your money accessible.
Once the account is open, transfer a portion of your paycheck into it immediately — before you spend anything else. This is the pay-yourself-first principle, and it’s one of the most powerful habits in personal finance.
Step 3: Start an Emergency Fund
Your first savings goal should be building an emergency fund. At 18, you might think you don’t need one — but unexpected expenses don’t care how old you are. A phone screen cracks, a bike gets stolen, a shift gets canceled last minute and you’re short for rent. These things happen, and without savings they force you into borrowing money or asking parents for help.
Your first emergency fund target should be $500-1,000. This covers the vast majority of common unexpected expenses without derailing your finances.
Save toward this goal first, before any other financial objective. Once you hit it, leave it alone — it’s not for planned spending, it’s for genuine emergencies only.
Step 4: Understand Your Deductions
Take a few minutes to read your pay stub line by line. The number at the top (gross pay) is not what lands in your account. For most U.S. workers, these are the main deductions:
- Social Security tax: 6.2% of your wages.
- Medicare tax: 1.45% of your wages. Together these are called FICA, and your employer pays a matching amount on top (IRS Topic 751).
- Federal income tax withholding, based on the Form W-4 you filled out when you were hired.
- State and local income tax, depending on where you live. A handful of states have no state income tax on wages.
- Optional deductions such as 401(k) contributions or health insurance premiums, if you signed up for them.
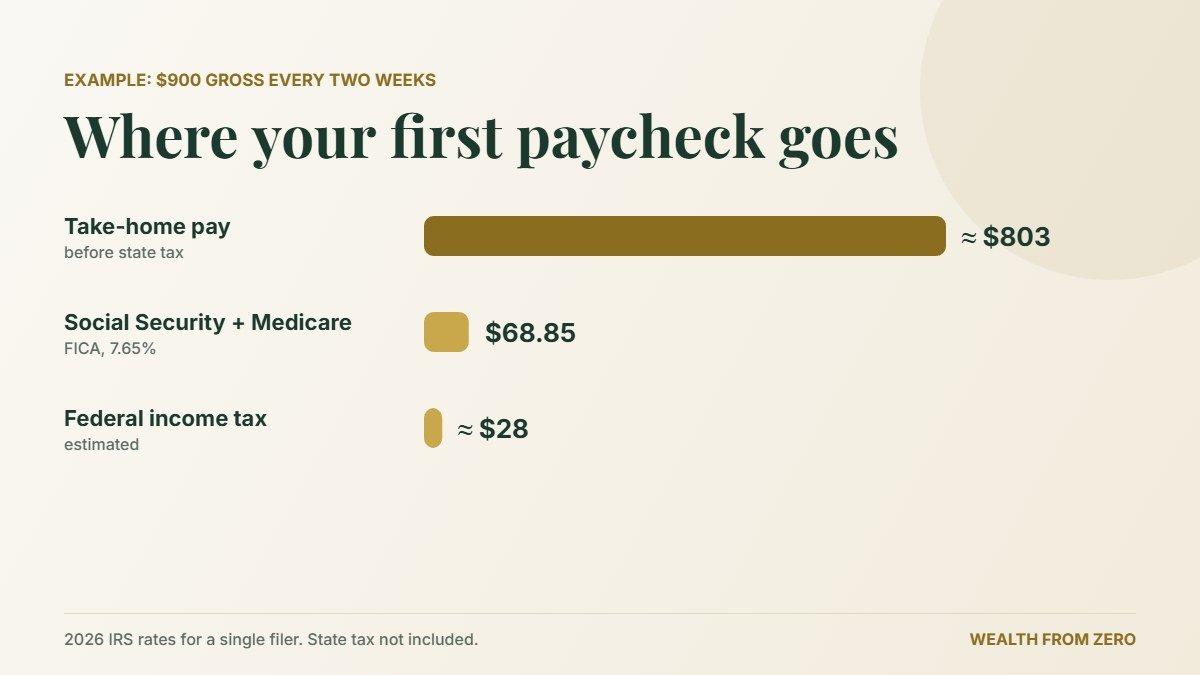
Example: say you earn $15 an hour, work 30 hours a week, and get paid every two weeks. Your gross pay is $900 per paycheck, or about $23,400 a year. FICA takes $68.85 (7.65%). For 2026, the standard deduction for a single filer is $16,100 and the first $12,400 of taxable income is taxed at 10% (IRS), so your federal income tax for the year would be roughly $730, or about $28 per paycheck. Before any state tax, you’d take home around $800 of that $900.
Two tips: fill out your W-4 carefully so you don’t have far too much or too little withheld, and if you earn little enough, you may get some or all of your federal withholding back when you file a tax return. The IRS Tax Withholding Estimator can check your numbers. Always budget from your take-home pay, not your gross pay.
Step 5: If Your Employer Offers a 401(k) Match, Take It
This applies if you’re an employee rather than doing gig or freelance work. Many employers match part of what you put into a 401(k). If yours matches 100% of contributions up to 3% of your salary, putting in 3% yourself means you get an instant 100% return on that money before any investment growth. Check your benefits paperwork or ask HR how the match works and whether it has a vesting schedule.
Retirement feels very far away at 18, but that is exactly why it matters: money invested now has decades to compound. For 2026, you can put up to $24,500 into a 401(k) and up to $7,500 into an IRA (IRS). You won’t come close to those limits on a first job, and you don’t need to. Even 3% to 5% of each paycheck is a strong start. If you have no workplace plan, a Roth IRA is a good place to begin, as long as you have earned income.
Step 6: Create a Simple Monthly Budget
Once you’ve received your first paycheck, you have real numbers to work with for the first time. Use them to build a simple monthly budget.
List your expected monthly income (your take-home pay) and your fixed expenses (rent if you’re paying it, phone bill, transport, any subscriptions). Subtract fixed expenses from income. Whatever remains is your discretionary income — the money available for food, socializing, clothing, and savings.
Decide what percentage of your income you want to save each month and treat that as a fixed expense. The rest is yours to spend as you choose, within the budget.
A simple starting framework is:
- 50% toward needs (essentials you must pay)
- 30% toward wants (things you enjoy but don’t strictly need)
- 20% toward savings
If 20% feels too high given your current income and expenses, start with 10% and increase it over time. The habit matters more than the percentage at this stage.
Step 7: Avoid Debt Unless Absolutely Necessary
At 18, credit cards, buy-now-pay-later schemes, and personal loans are more accessible than ever. Financial companies know that young people are lucrative customers — and they market aggressively to this age group.
Debt isn’t inherently evil. Used correctly, a credit card can build your credit score and offer consumer protections. But used carelessly — carrying a balance, making minimum payments, spending more than you earn — debt at 18 can create financial problems that take years to resolve.
General rules for debt at 18:
- Never carry a credit card balance if you can avoid it. Pay the full balance every month.
- Avoid buy-now-pay-later for everyday purchases. It encourages spending money you don’t have on things you don’t need.
- Only borrow for things that genuinely increase your future earning potential — education, tools for work, transport to get to a job.
Building a habit of living within your means from your very first paycheck is one of the most valuable financial foundations you can establish.
Step 8: Think About Your Financial Goals
Your first paycheck is also a good time to start thinking — even loosely — about what you want your financial future to look like. You don’t need a detailed 30-year plan at 18. But having some sense of direction helps you make better decisions with your money.
Some questions worth thinking about:
- Do you want to own a home one day? If so, saving toward a deposit early makes a significant difference.
- Do you want to travel? A dedicated travel fund means you save intentionally rather than scrambling for money when an opportunity arises.
- Do you want to start a business eventually? Building savings gives you the capital and financial cushion to take that risk when the time comes.
- What does financial security mean to you? Having a clear picture of what you’re working toward makes saving feel purposeful rather than arbitrary.
You don’t need to have all the answers at 18. But starting to ask the questions puts you significantly ahead of most people your age.
A Simple Action Plan for Your First Paycheck
Here’s a concrete, simple plan to put into action the moment your first paycheck arrives:
- Transfer 20% (or whatever you can manage) to a separate savings account immediately
- Read your pay stub and understand your deductions
- Check whether your employer offers a 401(k) match and make sure you’re enrolled
- Write down your monthly income and essential expenses
- Set a savings goal — aim for $500-1,000 as your first emergency fund target
- Decide on one financial goal beyond the emergency fund and open a dedicated savings pot for it
That’s it. Six steps. None of them are complicated, but together they set you up with habits and systems that most people twice your age still haven’t established.
The Bottom Line
Your first paycheck at 18 is more significant than it might appear. It’s not just money — it’s the beginning of a financial life. The habits you establish now will compound over the next several decades in ways that are difficult to fully appreciate in the moment.
Save before you spend. Build your emergency fund. Understand your pay stub. Avoid unnecessary debt. Set a budget. Think about your goals.
Do these things consistently, and your 18-year-old self will have given your future self an extraordinary gift.
Track your financial progress with our free calculator.
Your first paycheck sets the habit. Make it count by reading our beginner’s guide to budgeting and use our Savings Calculator to model where consistent saving takes you.
Frequently Asked Questions
How much of my first paycheck should I save?
Aim for at least 20% — ideally split between an emergency fund and a Roth IRA. If that’s too much, start with 10% and increase it with every raise. The habit matters more than the amount at first.
Should I open a Roth IRA with my first paycheck?
Yes, if you have any earned income. A Roth IRA is one of the best financial tools available — you contribute after-tax money and all growth and withdrawals in retirement are tax-free. The contribution limit for 2026 is $7,500 (or $8,600 if you’re 50+).
What should I NOT do with my first paycheck?
Lifestyle inflation — immediately spending more because you’re earning. The biggest wealth-building move is keeping your expenses close to what they were before you started working, and saving the difference.
Do I need to pay taxes on my first paycheck?
Yes — federal and state income tax, Social Security, and Medicare are typically withheld automatically by your employer. Review your W-4 to make sure the correct amount is being withheld, especially if you have multiple jobs.