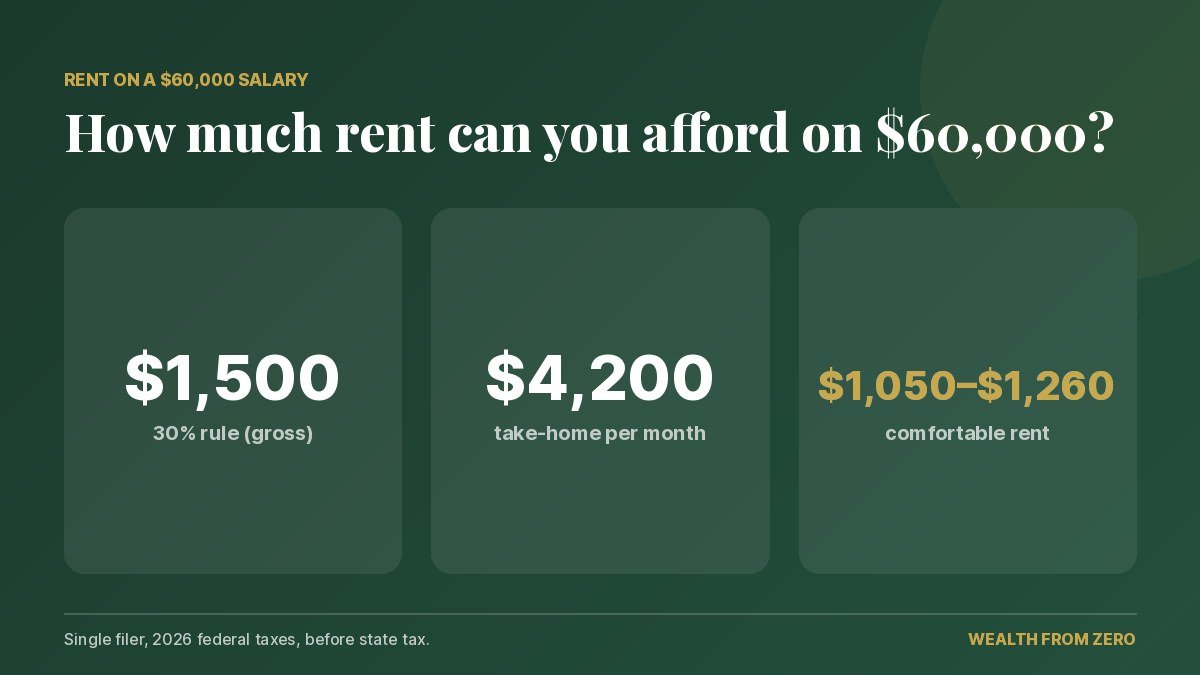
How much rent can I afford on $60,000 a year? The quick answer: about $1,500 a month under the classic 30% rule, the same figure most landlords’ 40× income test gives. But that number is based on pay before taxes. On your actual take-home pay of about $4,200 a month, a rent of $1,050–$1,260 is the range that still leaves real room to save. That buys the typical rent in some big metros, mostly in the Midwest and South, but not in most of them.
This guide works through the numbers the way a lender or a careful budgeter would: your take-home pay line by line, four ways to set a rent limit, how debt, a roommate or a 401(k) changes the answer, where the typical rent fits a $60,000 salary in the 50 largest U.S. metros, and what landlords will check when you apply.
Key numbers for a $60,000 salary
- 30% of gross income: $1,500/month
- Landlord 40× rule: $1,500/month (3× rule: about $1,670)
- Take-home pay (single, 2026 federal taxes): about $4,200/month
- Comfortable rent (25–30% of take-home): $1,050–$1,260
- Hourly equivalent: about $29 an hour at 40 hours a week
How Much Rent Can I Afford on $60,000? Four Ways to Calculate It
No single rule is “right.” Each one answers a slightly different question, so it helps to see all four side by side before you choose a target.
1. The 30% rule (gross income): $1,500
$60,000 × 30% ÷ 12 = $1,500 a month. The 30% line comes from U.S. housing policy, where households paying more than 30% of income for housing are counted as “cost-burdened.” It is a useful ceiling, but it ignores taxes, debt and where you live.
2. The landlord’s 40× rule: $1,500
Many landlords and property managers want your yearly gross income to be at least 40 times the monthly rent: $60,000 ÷ 40 = $1,500. Others ask for monthly income of three times the rent, which works out to about $1,670. This is the number that decides whether your application is approved, not whether the rent is comfortable.
3. The take-home method: $1,050–$1,260
This method starts from the money that actually lands in your account. Keeping rent at 25–30% of take-home pay gives $1,050–$1,260. It is the most conservative of the four, and the one we recommend if you want to save at least 15–20% of your pay.
4. The 50/30/20 method: up to $920
The 50/30/20 rule puts all your needs, not just rent, into 50% of take-home pay. With about $1,180 a month of other essentials (utilities, groceries, transportation, phone, insurance and minimum debt payments), the most you could spend on rent and still stay inside 50% is about $920. If your other essentials cost more, this cap drops dollar for dollar.
| Method | What it measures | Rent on $60,000 |
|---|---|---|
| 30% of gross | The traditional affordability ceiling | $1,500 |
| 40× rule | What many landlords require to approve you | $1,500 |
| 25–30% of take-home | A comfortable rent that leaves room to save | $1,050–$1,260 |
| 50/30/20 | Rent that keeps all needs at 50% of take-home | up to $920 |
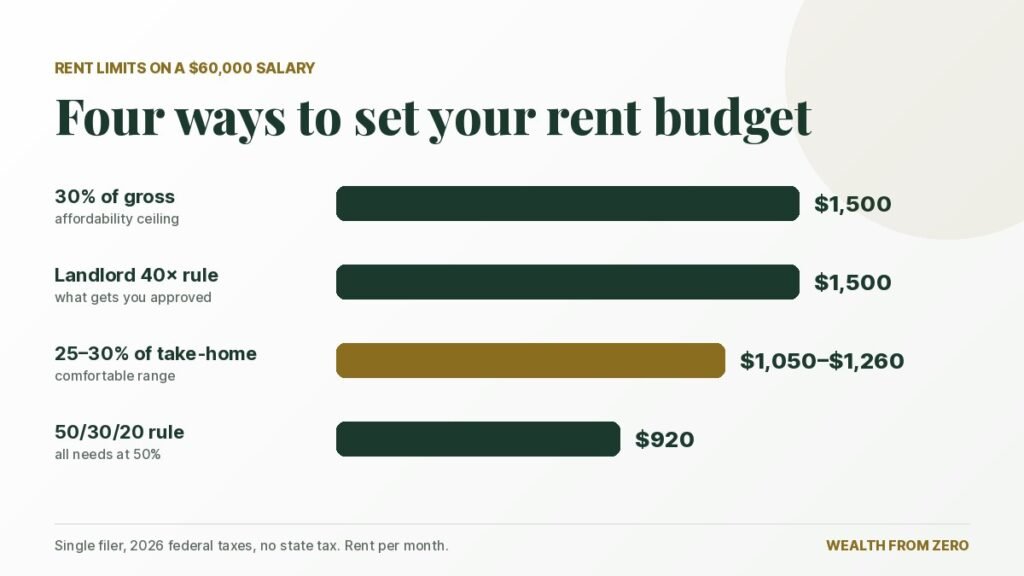
The strict 50/30/20 split gives the lowest number: about $920, because other essentials already use 28% of take-home. That is realistic only with a roommate or in a low-cost area. If you want a place of your own in a mid-priced metro, a 60/20/20 split is the more common compromise.
Your Take-Home Pay on a $60,000 Salary
| Per year | Per month | Every 2 weeks | |
|---|---|---|---|
| Gross salary | $60,000 | $5,000 | $2,308 |
| Federal income tax* | −$5,020 | −$418 | −$193 |
| Social Security + Medicare (7.65%) | −$4,590 | −$382 | −$177 |
| Take-home before state tax | $50,390 | $4,200 | $1,938 |
*Single filer, $16,100 standard deduction and 2026 federal tax brackets (IRS Rev. Proc. 2025-32), plus 7.65% for Social Security and Medicare. Your federal tax is about 8% of gross pay; your top bracket is 12%.
How your state changes the answer
State income tax is the biggest reason two people on the same salary have different budgets. Nine states don’t tax wages at all: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington and Wyoming. Elsewhere, rates and deductions vary a lot, so the table below uses simple round percentages to show the effect rather than any single state’s exact tax.
| If you live somewhere with… | Take-home per month | Comfortable rent |
|---|---|---|
| No state income tax | about $4,200 | $1,050–$1,260 |
| State tax of about 3% of pay | about $4,050 | $1,010–$1,220 |
| State tax of about 5% of pay | about $3,950 | $990–$1,180 |
The difference between a no-tax state and a 5% state is about $250 a month on $60,000, roughly $80 less you can comfortably put toward rent. Check your own state’s rate, or use a recent pay stub, before you sign a lease.
Step by Step: How Much Rent Can I Afford on $60,000 in My Budget?
- Start with your real take-home pay. Use a recent pay stub, not your salary. On $60,000 with no state tax, that is about $4,200 a month.
- Subtract your fixed non-rent costs. List utilities, groceries, transportation, phone, insurance and every minimum debt payment. Our example uses $1,180.
- Pay your savings first. Set aside 15% of take-home ($630) for your emergency fund and retirement before you look at listings.
- Leave room for everything else. Clothes, gifts, eating out and irregular costs need a line too. The example uses 25% of take-home ($1,050).
- What’s left is your rent ceiling. $4,200 − $1,180 − $630 − $1,050 = $1,340.
That $1,340 result lands between the comfortable range and the 30% rule. With 15% saved and a quarter of take-home left for wants, it is a realistic ceiling for a single renter without car or student loan payments. Run the same steps with your own numbers in our 50/30/20 budget calculator.
How Much Rent Can I Afford on $60,000 With Debt or a Roommate?
Using the same step-by-step ceiling of $1,340 as the starting point, here is how common situations change the most you can pay while still saving 15%:
| Situation | Maximum rent | Why |
|---|---|---|
| Base case (no extra debt) | $1,340 | Essentials of about $1,180/month, 15% saved |
| Student loan payment of $300/month | $1,040 | A debt payment comes straight out of what’s left for rent |
| Car payment of $450/month | $890 | Insurance is already in the base case |
| Splitting a two-bedroom with a roommate | a $2,520 unit | Your $1,260 share stays in the comfortable range |
What about a 401(k)? Putting 5% of your salary ($250 a month) into a pre-tax 401(k) lowers take-home pay by only about $220, because it also lowers your federal income tax. Since that money is savings, it counts toward your savings goal, so your rent ceiling barely moves. If your employer matches contributions, it is usually worth getting the full match before stretching for a bigger apartment.
On $60,000, a single loan payment is the difference between a one-bedroom of your own and needing a roommate in mid-priced metros. Paying down a car loan or a student loan early can be worth more to your housing options than a raise.
How Much Rent Can I Afford on $60,000 in the 50 Largest Metros?
We compared the 30% budget of $1,500 with the typical rent in each of the 50 largest U.S. metros, using the Zillow Observed Rent Index for August 2026, the same data behind our income needed to afford rent by city study. Zillow’s typical rent covers all home sizes, so a studio or one-bedroom usually costs less than the figure shown.
On $60,000, the typical rent fits the 30% rule in 9 of the 50 largest metros, mostly in the Midwest and South, plus Buffalo and Pittsburgh. In 12 more it costs more than 30% of gross pay but still less than 40% of take-home, which is manageable if your other bills are low. In the remaining 29, including most coastal metros, a typical rent would take more than 40% of take-home.
| Metro | Typical rent (Aug 2026) | Share of $60,000 take-home |
|---|---|---|
| Louisville, KY | $1,348 | 32% |
| Oklahoma City, OK | $1,388 | 33% |
| Memphis, TN | $1,400 | 33% |
| San Antonio, TX | $1,422 | 34% |
| Birmingham, AL | $1,433 | 34% |
| St. Louis, MO | $1,443 | 34% |
| Buffalo, NY | $1,449 | 34% |
| Cleveland, OH | $1,454 | 35% |
| Pittsburgh, PA | $1,469 | 35% |
| Columbus, OH | $1,521 | 36% |
| Cincinnati, OH | $1,522 | 36% |
| Detroit, MI | $1,524 | 36% |
| Kansas City, MO | $1,529 | 36% |
| Indianapolis, IN | $1,552 | 37% |
Typical rent at or under $1,500: 9 of 50 metros. Over 30% of gross but under 40% of take-home: 12. Over 40% of take-home: 29.
What a $60,000 Budget Looks Like at Three Rent Levels
Here is how $4,200 a month of take-home pay splits at three rents, with typical costs for a single renter:
| Monthly | $1,100 rent | $1,500 rent | $1,800 rent |
|---|---|---|---|
| Rent | $1,100 | $1,500 | $1,800 |
| Utilities + internet | $180 | $180 | $180 |
| Groceries | $400 | $400 | $400 |
| Transportation | $350 | $350 | $350 |
| Phone + insurance + minimum debt | $250 | $250 | $250 |
| Needs total | $2,280 (54%) | $2,680 (64%) | $2,980 (71%) |
| Left for savings and wants | $1,920 | $1,520 | $1,220 |
At $1,100 you could save 20% ($840) and still have about $1,080 a month for everything else. At $1,800 the same 20% leaves about $380, which works only if your other spending is modest.
Costs Beyond the Rent Check on a $60,000 Salary
When you ask how much rent you can afford on $60,000, count more than the advertised rent. Before you compare a listing with your $1,050–$1,260 target, add up:
- Utilities. Ask which ones are included. Heating and cooling can swing a lot by season and building age.
- Renters insurance. Many leases require it. It is usually inexpensive and covers your belongings and liability.
- Parking, pet rent and amenity fees. These recurring charges are often listed separately from rent.
- Commute. A cheaper place farther away can cost more overall once you add gas, transit or a second car.
- Move-in money. First month’s rent, a security deposit (often one month’s rent), application fees and movers. On a $1,500 apartment, plan for roughly $3,000–$3,900 upfront, kept separate from your emergency fund.
What Landlords Check When You Apply
Qualifying for an apartment and affording it are different questions. How much rent can I afford on $60,000 in a landlord’s eyes? The income test will approve rents up to about $1,500 (40× rule) or $1,670 (3× rule). Expect to show:
- Proof of income, such as recent pay stubs, an offer letter or tax returns if you are self-employed.
- A credit check. Landlords look at payment history and existing debt. If your credit is thin, our guide on building credit from scratch can help before your next move.
- Rental history and references from previous landlords.
- A guarantor or a larger deposit if your income or credit falls short. A guarantor helps you get approved, but it doesn’t make the rent any easier to pay each month.
Why Renting Below Your Maximum Pays Off
Choosing a $1,160 apartment instead of one at the full 30% limit of $1,500 frees about $340 a month. Invested every month for 10 years at a hypothetical 7% average annual return, that would grow to roughly $58,850. Returns are never guaranteed, but the habit of renting below what you can technically afford is one of the simplest ways to build savings without feeling deprived. See the math for your own numbers with our compound interest calculator.
How to Get More Apartment for Your Money on $60,000
- Aim below the maximum. Renting at $1,200 instead of $1,500 frees $3,600 a year, enough to build a starter emergency fund.
- Use your income to negotiate. At $60,000 you pass most income checks comfortably, which gives you room to ask for a concession or a longer lease at the same rent.
- In expensive metros, share. Where the typical rent tops $2,500, splitting it brings your share back near 30% of take-home.
- Time your move. Winter usually has less competition than summer.
- Ask what’s included. A slightly higher rent that includes utilities or parking can be cheaper overall.
- Get the 401(k) match first. If your employer matches, contributing enough to get it costs less than it looks and is worth more than extra square feet.
More ideas in how to save money on rent and how to negotiate rent.
How Much Rent Can You Afford at Other Salaries?
| Salary | 30% of gross | Take-home per month | Comfortable rent |
|---|---|---|---|
| $30,000 | $750 | about $2,190 | $550–$660 |
| $40,000 | $1,000 | about $2,860 | $720–$860 |
| $50,000 | $1,250 | about $3,530 | $880–$1,060 |
| $60,000 | $1,500 | about $4,200 | $1,050–$1,260 |
| $75,000 | $1,875 | about $5,130 | $1,280–$1,540 |
| $100,000 | $2,500 | about $6,600 | $1,650–$1,980 |
Frequently Asked Questions
Can I afford $2,000 rent on $60,000 a year?
$2,000 is 40% of gross pay and 48% of take-home, well above the usual guidelines. Most landlords using the 40× rule would want about $80,000 of income.
How much rent can I afford making $30 an hour?
Full time, $30 an hour is $62,400 a year: about $1,560 a month at 30% of gross, or roughly $1,090–$1,310 at 25–30% of take-home.
Is $60,000 a good salary for a single person?
It depends on where you live. In the nine metros where the typical rent fits the 30% rule, $60,000 leaves room to save 20% or more. In the most expensive metros, the typical rent alone would take 40% or more of take-home pay.
Should I use gross or take-home pay?
Landlords look at gross income. Your budget runs on take-home pay, so use the take-home number as your target and the 30% figure as your ceiling.
How much rent can a couple earning $60,000 combined afford?
The 30% rule still gives $1,500. Filing jointly usually lowers your federal tax compared with one person earning $60,000, so your take-home pay will be a little higher than in our single-filer table.
How much should I keep in savings after paying rent?
A common target is 15–20% of take-home pay, plus an emergency fund of three to six months of essential expenses. Our guide to how much emergency fund you need helps you size it.
The Bottom Line
So, how much rent can I afford on $60,000? Landlords will usually approve you up to about $1,500 a month, but a rent of $1,050–$1,260 is what keeps your budget healthy, with room to save and handle surprises. In the Midwest and South, that range buys a typical apartment; on the coasts, it usually means a smaller unit or a roommate. Either way, decide your savings first and let the rent fit around it.
How We Calculated These Numbers
Take-home pay assumes a single filer with no other income, the 2026 standard deduction of $16,100, 2026 federal income tax brackets and the 7.65% employee share of Social Security and Medicare. It excludes state and local taxes, health insurance and other payroll deductions unless noted. Typical rents are Zillow Observed Rent Index (ZORI) values for August 2026, smoothed, all homes plus multifamily, at the metro level. The 7% return used in the investing example is hypothetical and not a forecast.
Sources
- IRS Rev. Proc. 2025-32: 2026 tax brackets and standard deduction
- IRS Topic 751: Social Security and Medicare withholding rates
- Zillow Research: Zillow Observed Rent Index (ZORI), August 2026
- IRS: 401(k) contribution limits
This article is for education, not personal financial advice. Landlord requirements and state taxes vary; check the details for your situation.