Starting with no credit history can feel like a catch-22: you need credit to build credit. But it’s more solvable than it seems. Millions of Americans have no credit file at all, or too little history to generate a score. This guide shows you the fastest, safest ways to build credit from zero. Related: how credit scores are calculated.
Without a credit history, renting an apartment becomes harder. Getting approved for a mortgage feels impossible. Even some employers run credit checks as part of their hiring process. And when you do need to borrow money — for a car, an emergency, or eventually a home — the interest rates available to people with no credit history are significantly worse than those available to people with established, positive credit.
Building credit from scratch is entirely achievable — and with the right approach, you can establish a meaningful credit history within 6-12 months. This guide explains exactly how credit scores work, why they matter, and the most effective strategies for building credit when you’re starting from zero.
Federal Reserve data shows that borrowers with higher credit scores pay significantly less interest over a lifetime — the difference between a good and poor credit score on a 30-year mortgage alone can exceed $100,000 in total interest paid.
How Credit Scores Work
Before building credit, it’s essential to understand what a credit score actually is and what factors determine it.
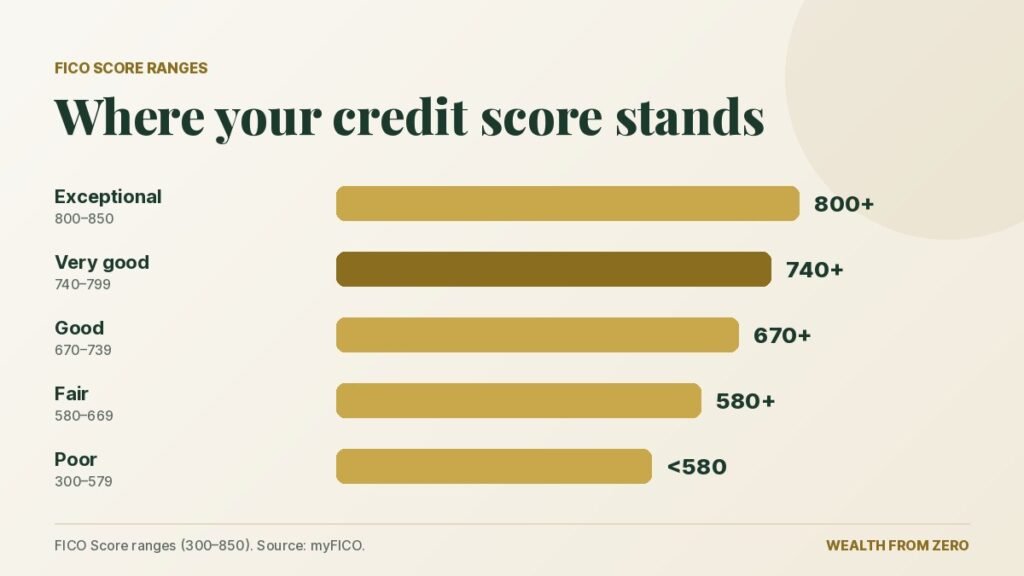
A credit score is a numerical representation of your creditworthiness — how likely you are to repay debts based on your past financial behavior. In the US, the most widely used scoring model is the FICO score, which ranges from 300 to 850. VantageScore, a competing model created by the three major credit bureaus (Equifax, Experian and TransUnion), uses the same 300 to 850 range.
Here’s how FICO scores are categorized:
| Credit Score Range | Rating | Impact |
|---|---|---|
| 800-850 | Exceptional | Best rates on all products |
| 740-799 | Very Good | Near-best rates available |
| 670-739 | Good | Most mainstream products available |
| 580-669 | Fair | Limited options, higher rates |
| 300-579 | Poor | Very limited options, highest rates |
Your FICO score is calculated from five factors, weighted as follows:
| Factor | Weight | What It Measures |
|---|---|---|
| Payment History | 35% | Whether you pay on time |
| Credit Utilization | 30% | How much of your available credit you use |
| Length of Credit History | 15% | How long you’ve had credit accounts |
| Credit Mix | 10% | Variety of credit types you have |
| New Credit | 10% | How often you apply for new credit |
According to myFICO, payment history is by far the most important factor — making on-time payments consistently is the single most powerful thing you can do to build and maintain a strong credit score.
See what each credit score range means and how your score is calculated for more detail.
Why Building Credit Matters
The financial benefits of a strong credit score are substantial and far-reaching:
Lower interest rates on loans and mortgages. The difference in interest rates between someone with excellent credit and someone with poor credit can be 3-5% on a mortgage — potentially tens of thousands of dollars over the life of the loan.
Consider a $250,000 30-year mortgage:
| Credit Score | Approximate Interest Rate | Monthly Payment | Total Interest Paid |
|---|---|---|---|
| 760-850 | 6.5% | $1,580 | $318,868 |
| 700-759 | 6.7% | $1,613 | $330,832 |
| 680-699 | 6.9% | $1,646 | $342,782 |
| 660-679 | 7.1% | $1,679 | $354,746 |
| 640-659 | 7.5% | $1,748 | $379,392 |
| 620-639 | 8.0% | $1,834 | $410,310 |
The difference between excellent credit and poor credit on this mortgage is $254 per month — $91,442 over 30 years. Your credit score is genuinely worth tens of thousands of dollars.
Better rental terms. Most landlords run credit checks on prospective tenants. A strong credit history makes it significantly easier to rent a desirable property and may reduce or eliminate the need for a larger security deposit.
Lower insurance premiums. In many US states, insurance companies use credit-based insurance scores to determine premiums for car and home insurance. Better credit often means lower premiums.
Access to better financial products. Premium credit cards with valuable rewards, cashback, and travel benefits are typically only available to people with good to excellent credit.
Strategy 1: Get a Secured Credit Card
A secured credit card is the most accessible and effective tool for building credit from scratch. Unlike a regular credit card — which extends you credit based on your creditworthiness — a secured card requires you to deposit money upfront as collateral, which becomes your credit limit.
For example, you might deposit $300-500 to open a secured card with a $300-500 credit limit. The card then works like any other credit card — you make purchases and pay the bill each month. Your payment behavior is reported to the credit bureaus, building your credit history.
The key rules for using a secured card to build credit:
Use it for small, regular purchases. A recurring subscription, a weekly grocery trip, or a monthly utility bill are ideal. The goal is consistent, manageable usage — not maxing out the card.
Pay the full balance every month. Never carry a balance on a secured card. Pay the full statement balance by the due date, every single month without exception. This builds a perfect payment history — the most important factor in your credit score — without paying any interest.
Keep your utilization below 30%. If your credit limit is $300, never have more than $90 charged to the card at any time. Credit utilization — the percentage of your available credit you’re using — has a significant impact on your score. Lower is better, with under 10% being ideal.
After 12-18 months of responsible use, many secured card issuers automatically upgrade you to a regular unsecured card and return your deposit. By this point, you’ll have a meaningful credit history.
Popular secured cards with no annual fee include the Discover it Secured Credit Card and the Capital One Platinum Secured Credit Card in the US.
Strategy 2: Become an Authorized User on Someone Else’s Account
If you have a family member or close friend with a long-standing credit card account and excellent payment history, asking to be added as an authorized user is one of the fastest ways to build credit history.
When you’re added as an authorized user, the entire history of that account — including its age, credit limit, and payment history — is added to your credit report. If the primary cardholder has had the account for ten years and never missed a payment, that positive history immediately strengthens your credit profile.
You don’t necessarily need to use the card. Simply being listed as an authorized user is enough to benefit from the account’s history. The primary cardholder remains responsible for all charges and payments.
This strategy only works if the primary cardholder has excellent credit habits. Being added to an account with missed payments or high utilization can actually harm your credit rather than help it.
Strategy 3: Apply for a Credit Builder Loan
A credit builder loan is a product specifically designed to help people establish credit history. Unlike a traditional loan where you receive money upfront, a credit builder loan works in reverse: the lender holds the loan amount in a savings account while you make monthly payments. Once all payments are made, you receive the money.
The loan itself is almost irrelevant — the purpose is the payment history it generates. Each monthly payment is reported to the credit bureaus, building a track record of on-time payments that improves your credit score.
Credit builder loans are typically offered by credit unions, community banks, and specialist providers like Self (formerly Self Lender) in the US. Loan amounts are typically $300-1,000, with terms of 12-24 months and monthly payments of $25-50.
The additional benefit is that completing a credit builder loan gives you a small savings amount — the loan principal — at the end, which could form the start of your emergency fund.
Strategy 4: Report Rent and Utility Payments
In the US, services like Experian Boost, RentTrack, and Rental Kharma allow you to add rent and utility payment history to your credit report — payments you’re already making that wouldn’t otherwise count toward your credit score.
Experian Boost is particularly accessible — it’s free, takes a few minutes to set up, and can immediately improve your Experian credit score by adding positive payment history from utility and phone bills.
In the U.S., some landlords and rent-reporting services can report your on-time rent payments to one or more of the credit bureaus. Whether it helps your score depends on which bureau receives the data and which scoring model a lender uses, so ask before paying for a rent-reporting service.
If you’re already paying rent and utilities on time every month, taking five minutes to sign up for these services adds value from payments you’re making anyway.
Strategy 5: Apply for a Store Credit Card
Store credit cards — offered by retailers like Amazon, Target, or department stores — typically have lower credit score requirements than mainstream credit cards, making them more accessible to people with limited credit history.
Used responsibly — small purchases, full balance paid every month — a store card builds credit history in the same way as any other credit card. The downside is that store cards typically have high interest rates, so carrying a balance is expensive. Treat a store card exactly like a secured card: use it for small regular purchases and pay it off in full every month.
What to Avoid When Building Credit From Scratch
Applying for multiple credit products simultaneously. Each credit application generates a hard inquiry on your credit report, which temporarily reduces your score by a few points. Multiple applications in a short period signal financial distress to lenders. Space applications at least 3-6 months apart.
Missing payments. A single missed payment can significantly damage a credit score that took months to build. Set up automatic minimum payments for every credit account so you never accidentally miss a due date — then pay the full balance manually before the due date each month.
Maxing out credit cards. High credit utilization — using a large percentage of your available credit — negatively impacts your score. Keep balances below 30% of your credit limit at all times, and ideally below 10%.
Closing old accounts. Length of credit history accounts for 15% of your FICO score. Closing old credit accounts shortens your average account age and reduces your available credit — both of which can hurt your score.
Falling for credit repair scams. Companies that promise to “fix” your credit for a fee almost never deliver what they promise. Legitimate negative information on your credit report cannot be legally removed before it naturally expires (typically after 7 years). The only genuine way to build good credit is through consistent positive behavior over time.
How Long Does It Take to Build Credit From Scratch?
Building credit from scratch is a process measured in months, not days. Here’s a realistic timeline:
| Timeframe | Expected Progress |
|---|---|
| Month 1-2 | Credit file opened, first accounts appearing |
| Month 3-6 | Initial credit score generated (typically 580-650) |
| Month 6-12 | Score improving with consistent on-time payments |
| Month 12-18 | Score potentially reaching 670+ (Good range) |
| Year 2-3 | Score potentially reaching 720+ (Very Good range) |
| Year 5+ | Score potentially reaching 750+ (Excellent range) |
These timelines assume perfect payment history, low credit utilization, and no negative marks on your credit report. Individual results vary based on the specific accounts you open and how you manage them.
Monitoring Your Credit Score
As you build your credit, monitoring your progress is both motivating and practical — catching any errors or fraudulent accounts early prevents them from damaging your score.
Free credit monitoring options include:
- Credit Karma — free weekly credit score updates from TransUnion and Equifax
- Experian — free monthly Experian score
- AnnualCreditReport.com (US) — free annual credit reports from all three bureaus
Check your credit report at least once per year for errors. Common errors include accounts that don’t belong to you, incorrect payment statuses, and outdated negative information that should have been removed. Disputing errors with the relevant credit bureau can sometimes improve your score quickly.
Which Secured Card Should You Start With?
For a first card with no credit history, what matters most is that the card reports to all three bureaus (Equifax, Experian and TransUnion), has no annual fee, and has a clear path to “graduating” to a regular unsecured card. Card terms change frequently, so confirm the current deposit, fees and graduation policy on the issuer’s site before applying.
| What to Check | What You Want | Why It Matters |
|---|---|---|
| Bureau reporting | Reports to all 3 bureaus | If a card doesn’t report, it doesn’t build your score |
| Annual fee | $0 | A fee on a low-limit card eats into your available credit |
| Security deposit | An amount you can afford to lock up | The deposit usually becomes your credit limit |
| Graduation policy | Automatic reviews for an upgrade | Lets you get your deposit back and move to an unsecured card |
| Credit check | None or soft pull if you have thin/damaged credit | Avoids a hard inquiry on a file with no history |
The simple system: open one secured card, put one small recurring bill on it (a streaming subscription or a tank of gas), and pay the full statement balance every month. Don’t add a second card until you’ve managed the first one cleanly for six months or more.
Month-by-Month: What Building Credit From Zero Looks Like
| Timeline | What Happens | What to Do |
|---|---|---|
| Month 0 | You open your first account (secured card or credit-builder loan) | Set up autopay for at least the minimum as a safety net |
| Months 1–5 | Your account reports to the bureaus each month, but FICO doesn’t have enough history yet | Pay the full balance every month; keep the reported balance low |
| Month 6 | FICO typically needs at least one account open for six months before it can generate a score | Check your score for free (many issuers show your FICO Score in their app) |
| Months 6–12 | Each on-time payment strengthens your history; many issuers review secured accounts for an upgrade | Keep utilization under 10%; accept an upgrade if offered |
| Year 1–2 | A clean history and low utilization usually move you into the “Good” range (670+) | Consider a second, unsecured card to add available credit |
Everyone’s timeline is different — it depends on utilization, whether you add other accounts, and any negative marks — but the pattern is consistent: the first six months are about establishing a file, and the next year is about proving you manage it well. To understand exactly what each score range unlocks, see our credit score explained guide.
The Credit Utilization Secret Most People Miss
Credit utilization (30% of your score) is calculated at the moment your card issuer reports your balance to the credit bureaus — which is typically your statement closing date, not your payment due date. This means even if you pay your balance in full every month, a high statement balance can drag down your score.
The fix: Make a small payment 5-7 days before your statement closes to bring your balance below 10% of your limit before the balance gets reported. If your limit is $1,000, aim to have less than $100 showing on your statement — regardless of whether you pay it off immediately after.
Free Credit Monitoring: How to Track Your Progress
- AnnualCreditReport.com — the only federally mandated free credit report service. Get your full report from all three bureaus (Equifax, Experian, TransUnion) once per year. Check for errors — 1 in 5 Americans has an error on their credit report that could be costing them points.
- Credit Karma — free TransUnion and Equifax scores updated weekly. Useful for tracking trends, though the VantageScore they show may differ from your FICO score used by lenders.
- Credit card issuer dashboards — many credit cards (Discover, Capital One, Chase) now show your FICO score for free in their app. This is the same score lenders actually use.
Frequently Asked Questions
How long does it take to build credit from scratch?
Most people can achieve a “good” credit score (670+) within 6-12 months of responsible credit use. A “very good” score (740+) typically takes 1-2 years of consistent on-time payments and low utilization.
What’s the fastest way to build credit with no history?
A secured credit card or a credit-builder loan. Use the card for one small purchase per month, pay the full balance before the due date, and you’ll start building a positive payment history immediately.
Does checking my own credit score hurt it?
No — checking your own score is a “soft inquiry” and has no effect on your credit. Only “hard inquiries” (when a lender checks your credit for a loan application) can temporarily lower your score by a few points.
What is a good credit score for a first-time borrower?
Any score above 670 is considered “good” and will qualify you for most standard loans and credit cards. Above 740 is “very good” and will get you better interest rates. Above 800 is “exceptional” and gets you the best rates available.
How much does a low credit score cost me?
Significantly. On a 30-year $300,000 mortgage, the difference between a 620 score and a 760 score can mean paying $50,000-$100,000 more in interest over the life of the loan.