Living paycheck to paycheck is one of the most stressful financial situations a person can be in. You work hard all month, your pay arrives, and within days — sometimes hours — it’s already gone. Bills, rent, food, transport. And then the waiting begins again until the next payday.
Below are the steps to break the cycle, starting with the ones that free up cash fastest.
For people on minimum wage, this cycle can feel completely inescapable. When every penny is already spoken for before it even arrives, the idea of saving money or getting ahead financially can seem like a cruel joke.
But here’s what most people in this situation don’t realize: breaking the paycheck-to-paycheck cycle on a minimum wage is possible. It’s not easy, and it doesn’t happen overnight. But with the right mindset, the right strategies, and consistent small actions, you can start to create breathing room in your finances — even on a very tight income.
Why So Many People Get Stuck Living Paycheck to Paycheck
Before we talk about solutions, it’s worth understanding why the paycheck-to-paycheck cycle is so hard to escape in the first place.
The most obvious reason is that minimum wage simply doesn’t go very far. In many cities and countries, the minimum wage is not enough to comfortably cover basic living costs — rent, food, transport, utilities — let alone save anything. This is a systemic problem, and it’s important to acknowledge it honestly. Related: save money fast on a low income.
But there are also behavioral factors at play. Without a clear budget, money tends to disappear without any clear sense of where it went. Small daily expenses — a coffee here, a convenience store snack there, a subscription you forgot about — add up to significant amounts over a month. And when money is tight, the psychological weight of financial stress can lead to small impulsive purchases as a form of emotional relief, which only makes the situation worse.
Understanding both the structural and behavioral factors helps you target your efforts where they’ll make the most difference.
According to BLS Consumer Expenditure data, the average U.S. household spent about $78,500 in 2024, yet most people can’t account for where a significant portion goes without a written budget.
According to the Federal Reserve’s Economic Well-Being of U.S. Households report (published May 2026), 37% of US adults would not cover an unexpected $400 expense with cash or its equivalent, and 12% said they could not pay it by any means. But income isn’t the primary driver — studies consistently show that lifestyle inflation keeps middle-income earners stuck just as firmly as low-income earners. When income rises, expenses rise proportionally, leaving the same zero at the end of each month.
| Root Cause | How Common | Fix |
|---|---|---|
| No written budget | Very common | Start with the 50/30/20 rule |
| Lifestyle inflation (spending rises with income) | Extremely common | Automate savings before spending |
| No emergency fund (emergencies become debt) | Very common | Build $1,000 starter fund first |
| High-interest debt consuming income | Common | Pay off highest-rate debt first |
| Subscriptions and small recurring costs | Very common | Audit all recurring charges monthly |
The three root causes aren’t what most people think:
- No system. Without a budget, money moves toward convenience — subscriptions, dining out, impulse purchases. Decisions happen by default, not by choice.
- No buffer. Without an emergency fund, every unexpected expense (car repair, medical bill) becomes a credit card balance that compounds at 22%. Breaking the cycle requires a $1,000 buffer before anything else.
- Lifestyle inflation. Each raise gets absorbed into spending before it can build wealth. The most powerful intervention: automate savings increases every time income increases, before lifestyle adjusts.
Use our Budget Calculator to see exactly where your money is going and find the biggest levers to pull.
Step 1: Know Exactly Where Your Money Is Going
The first and most important step is to track every single penny you spend for one full month. Not an estimate — every actual transaction, no matter how small.
Most people who do this for the first time are genuinely shocked by the results. Money that felt like it just “disappeared” turns out to have gone on specific, trackable things. A daily coffee. Multiple streaming subscriptions. Convenience food because there was nothing planned for dinner. Small impulse purchases that felt insignificant in the moment.
You can’t change what you can’t see. Tracking your spending gives you the information you need to make better decisions.
Use a free app, a simple spreadsheet, or even a notebook. The tool doesn’t matter — the habit does.
Step 2: Build a Bare-Bones Budget
Once you know where your money is going, build a bare-bones budget. This is different from a normal budget — it’s a stripped-back version that covers only the absolute essentials.
List your fixed essential expenses first:
- Rent or housing costs
- Utility bills
- Groceries (food only, not dining out)
- Transport to work
- Any essential debt minimum payments
- Phone bill (if needed for work)
Add these up and subtract from your monthly take-home pay. Whatever is left is what you have to work with for everything else — and potentially for starting to save.
If your essential expenses already eat up more than your entire income, you have a more serious situation that requires either reducing fixed costs (moving somewhere cheaper, finding a roommate) or increasing income (which we’ll cover shortly).
Step 3: Find and Eliminate the Leaks
Now look at your spending tracking from Step 1 and identify the non-essential expenses — the leaks in your financial bucket. These are the things you’re spending money on that aren’t strictly necessary.
Common leaks for people on minimum wage include:
- Multiple streaming subscriptions (Netflix, Spotify, Disney+, etc.)
- Daily coffee or energy drinks from shops
- Convenience food and takeaways
- Lottery tickets or gambling apps
- Impulse purchases online, especially late at night
You don’t necessarily need to eliminate all of these forever. But temporarily cutting them while you build financial stability can free up more money than you might expect. Even saving $50-100 per month that was previously being leaked away is a meaningful step forward.
Step 4: Reduce Your Biggest Expenses
For people on minimum wage, the biggest opportunity for savings is usually in the three major expense categories: housing, food, and transport.
Housing: If you’re spending more than 30% of your income on rent, your housing costs are likely contributing significantly to the paycheck-to-paycheck cycle. Consider getting a roommate, moving to a cheaper area, or exploring whether you qualify for any housing assistance programs.
Food: Groceries are one of the most controllable expenses. Meal planning, buying store-brand products, reducing meat consumption, and shopping at discount supermarkets can cut your food bill significantly. Cooking in bulk and freezing portions is particularly effective for people with busy schedules.
Transport: If you’re paying for a car, consider whether public transport, cycling, or carpooling could be cheaper. Car payments, insurance, fuel, and maintenance add up to a surprisingly large monthly cost.
Step 5: Build a Tiny Emergency Fund First
This might seem counterintuitive when you’re already struggling, but building even a tiny emergency fund — just $200-500 — is one of the most important things you can do to break the paycheck-to-paycheck cycle.
Here’s why: without any savings buffer, every unexpected expense goes on a credit card or causes you to skip another bill. This creates a debt spiral that makes the cycle even harder to escape. With even a small emergency fund, you can handle minor unexpected expenses without going into debt.
Save this money first, before anything else. Even $10 or $20 per week adds up. Keep it in a separate account so you’re not tempted to spend it.
Step 6: Find Ways to Increase Your Income
On minimum wage, there’s a limit to how much you can cut. At some point, the most powerful lever available to you is increasing your income — even slightly.
Some options to consider:
Ask for more hours. If your employer offers overtime or additional shifts, taking them temporarily while you stabilize your finances can make a significant difference.
Look for a higher-paying job. Minimum wage isn’t a life sentence. Even a small pay increase — moving from $10 to $12 per hour — adds up to over $4,000 extra per year. Regularly applying for better-paying positions in your field or adjacent fields is a worthwhile long-term strategy.
Start a small side hustle. Even earning an extra $100-200 per month through dog walking, babysitting, selling items online, or doing odd jobs in your neighborhood can provide the breathing room that makes all the difference.
Explore benefits and assistance programs. Many people on low incomes are entitled to government benefits, tax credits, or assistance programs that they’re not currently claiming. Research what’s available in your area — you may be leaving money on the table.
Step 7: Change Your Relationship With Money
Breaking the paycheck-to-paycheck cycle on minimum wage is as much a mindset shift as it is a practical one. When money is very tight, it’s easy to fall into either extreme: either obsessing over every penny to the point of anxiety, or giving up entirely because it feels hopeless.
The healthier approach is somewhere in the middle. Be intentional with your money without being miserable about it. Make conscious decisions rather than letting money slip away by default. And be patient — progress on a minimum wage is slow, but it is real and it does compound over time.
Every week you don’t go further into debt is progress. Every month you manage to save even a small amount is progress. Every time you choose a home-cooked meal over a takeaway, that’s progress too.
A Simple 90-Day Plan
| Month | Goal | Action |
|---|---|---|
| Month 1 | Know your numbers | Track every expense for 30 days |
| Month 2 | Build $500 buffer | Cut 3 expenses, redirect to savings |
| Month 3 | Reach $1,000 emergency fund | Automate $100+/week to savings |
| Month 4–6 | Break the cycle | Budget monthly, increase savings rate |
The Bottom Line
Breaking the paycheck-to-paycheck cycle on minimum wage is one of the hardest financial challenges there is — but it’s not impossible. Track your spending, build a bare-bones budget, eliminate the leaks, reduce your biggest expenses, and find ways to bring in even a little extra income.
Start with just one change this week. Track your spending for seven days. See where your money is actually going. That single step can be the beginning of a real and lasting change in your financial situation.
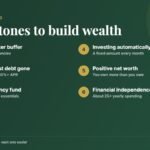
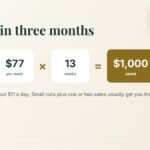
The first financial goal when you stop living paycheck to paycheck is building a $1,000 emergency fund. After that, work toward saving $1,000 in 3 months to build real momentum.
Use our Savings Calculator to see how quickly your first $1,000 buffer can grow. And: how to budget for beginners — the system that breaks the paycheck-to-paycheck cycle.
Frequently Asked Questions
What does it mean to live paycheck to paycheck?
It means your income barely covers your monthly expenses, leaving little or nothing for savings or emergencies. According to the CFPB, most people in this cycle aren’t overspending on luxuries — they’re dealing with stagnant wages, rising costs, and no financial cushion.
How do I stop living paycheck to paycheck on minimum wage?
Start by tracking every expense for one month — most people find $100-$200 in spending they can cut. Then build a $500-$1,000 starter emergency fund. That cushion alone breaks the cycle for many people, because one unexpected expense no longer sends you into debt. For a deeper dive, read our Frugal Living: 50 Habits That Actually Work.
What’s the fastest way to get extra money when you’re broke?
Selling items you own (electronics, clothes, furniture), picking up gig work (DoorDash, TaskRabbit, Fiverr), or offering services locally (cleaning, lawn care, tutoring). Most people can generate $200-$500 in a single weekend without any special skills.
Is it possible to stop living paycheck to paycheck on minimum wage?
Yes, but it requires intentional changes to both spending and saving habits. The goal isn’t to have a lot of money — it’s to create a small gap between what you earn and what you spend. Even saving $20-30 a week starts to break the cycle over time.
Why do people live paycheck to paycheck even with a decent income?
Lifestyle inflation is the main culprit — as income rises, spending tends to rise with it. Many people earning good salaries still live paycheck to paycheck because they’ve never built the habits of budgeting, saving, and living below their means.
What is the first step to stop living paycheck to paycheck?
Track every penny you spend for one month. Most people are genuinely surprised by where their money goes. Once you can see your spending clearly, you can identify what to cut and where to redirect money toward savings.
How do I build savings when I have nothing left at the end of the month?
Automate a small transfer to savings the moment your paycheck arrives — even $10 or $20. Saving what’s left over never works because there’s never anything left. Pay yourself first, even if the amount feels insignificant.
Should I look for a higher paying job to break the cycle?
Increasing your income is one of the most effective ways to break the paycheck to paycheck cycle, but it’s not the only lever. Building better money habits now means that when your income does increase, you’ll actually get ahead instead of just spending more.
How long does it take to stop living paycheck to paycheck?
It depends on your income, expenses, and how aggressively you make changes. Most people start to see a meaningful difference within 2-3 months of consistently budgeting and automating savings. The key is not to give up when progress feels slow.
Is it possible to save money on minimum wage?
Yes, though it requires cutting expenses to the bone and often finding ways to increase income. Even $25-$50 per month matters — it builds the habit and the buffer that prevents small problems from becoming financial crises.