For the official 2026 Roth IRA contribution limits, income phase-outs, and withdrawal rules, see the IRS Roth IRA page.
A Roth IRA might be the single best financial account available to most Americans under 50 — and most people either don’t know what it is, don’t think they qualify, or assume it’s complicated to open. None of those things are true. Here’s everything you need to know to open one today. This complete Roth IRA for beginners guide covers everything you need to open one today.
In 2026, a 25-year-old who maxes out a Roth IRA every year until age 65 at a 7% average annual return ends up with approximately $1.5 million — completely tax-free. No tax on the gains. No tax on withdrawals in retirement. That’s the Roth IRA’s superpower, and it’s why financial advisors consistently call it the best retirement account for most young earners. See our full guide on ETF vs Index Fund comparison.
What Is a Roth IRA?
A Roth IRA (Individual Retirement Account) is a tax-advantaged retirement savings account where you contribute money that has already been taxed — and then it grows completely tax-free. When you withdraw the money in retirement (after age 59½), you pay zero tax on the gains, no matter how much they’ve grown. You also don’t have to take required minimum distributions at any age, unlike traditional IRAs and 401(k)s, which means you can let the account compound indefinitely if you don’t need the money. Related: Roth IRA vs 401(k): which should you choose.
The key distinction from a traditional IRA: Roth = pay tax now, none later. Traditional = pay no tax now, full tax later. For most people under 40 who expect to be in a higher tax bracket in retirement than they are today, Roth wins by a wide margin.
Roth IRA vs Traditional IRA: Which Should You Choose?
| Roth IRA | Traditional IRA | |
|---|---|---|
| Tax on contributions | After-tax (no deduction) | Pre-tax (tax deductible) |
| Tax on growth | Tax-free | Tax-deferred |
| Tax on withdrawals | None | Taxed as income |
| 2026 contribution limit | $7,500 ($8,600 if 50+) | $7,500 ($8,600 if 50+) |
| Income limit (2026) | Under ~$168,000 single / $252,000 married | No income limit |
| Required minimum distributions | None | Starting at age 73 |
| Early withdrawal of contributions | Anytime, penalty-free | 10% penalty + taxes |
| Best for | Young earners, lower tax bracket now vs retirement | High earners who expect lower taxes in retirement |
For most people under 50: choose the Roth IRA. The tax-free growth on decades of compound returns almost always outweighs the immediate tax deduction of a traditional IRA — especially when you’re in a lower tax bracket early in your career.
2026 Roth IRA Contribution Limits and Income Rules
The IRS sets annual contribution limits and income phase-outs for Roth IRA eligibility:
| Filing Status | Full Contribution | Phase-Out Range | No Contribution Allowed |
|---|---|---|---|
| Single / Head of Household | Under $153,000 | $153,000 – $168,000 | Over $168,000 |
| Married Filing Jointly | Under $242,000 | $242,000 – $252,000 | Over $252,000 |
| Married Filing Separately | Under $10,000 | $0 – $10,000 | Over $10,000 |
2026 contribution limit: $7,500 per year (under 50) or $8,600 (50 and older). You can contribute to a Roth IRA regardless of whether you also have a 401(k) — they’re separate accounts with separate limits. You can contribute to both in the same year.
If your income is above the Roth IRA limit, look into the Backdoor Roth IRA strategy — contributing to a non-deductible traditional IRA and immediately converting it to Roth. This is a legal and widely used workaround for high earners.
How to Open a Roth IRA in 4 Steps
Step 1: Choose a brokerage. The best Roth IRA providers in 2026 for beginners are Fidelity, Charles Schwab, and Vanguard. All three offer $0 account minimums, fractional shares, and excellent index funds. Fidelity is the top recommendation for most beginners: their FZROX fund has a 0% expense ratio, and the interface is clean and beginner-friendly.
Step 2: Fill out the application. Go to Fidelity.com (or your chosen provider) and click “Open an Account” → Roth IRA. You’ll need your Social Security number, address, and bank account information. The whole process takes about 10 minutes.
Step 3: Fund the account. Link your bank account and transfer money in. You can contribute up to $7,500 for the 2026 tax year (deadline: April 15, 2027). You don’t have to contribute the full $7,500 at once — set up a monthly automatic contribution of $625/month to max it out over the year.
Step 4: Choose your investments. Opening a Roth IRA does not automatically invest your money — you have to choose what to buy inside the account. For most beginners, the answer is simple: an S&P 500 index fund or total market index fund. At Fidelity: FZROX (0% fee) or FXAIX (0.015% fee). At Vanguard: VTI (0.03% fee). At Schwab: SWTSX (0.03% fee).
Best Roth IRA Investments for Beginners in 2026
| Investment | Expense Ratio | What It Holds | Best For |
|---|---|---|---|
| FZROX (Fidelity) | 0.00% | Total US market (~3,000 stocks) | Fidelity account holders, lowest-fee option |
| FXAIX (Fidelity) | 0.015% | S&P 500 — top 500 US companies | Simplest, most proven index fund |
| VTI (Vanguard) | 0.03% | Total US market | Vanguard account holders |
| SWTSX (Schwab) | 0.03% | Total US market | Schwab account holders |
| Target Date Fund 2055 | 0.10–0.15% | Mix of stocks/bonds, auto-adjusts | Truly hands-off approach |
For 95% of Roth IRA beginners, one of the first four options above is the correct choice. Pick the fund that matches your brokerage, set up automatic monthly contributions, and do not touch it for 30+ years. The results speak for themselves: use our Investment Return Calculator to see exactly what $625/month at 7% average return grows to over your working life.
The Roth IRA Growth Timeline: Real Numbers
| Starting Age | Monthly Contribution | At Age 65 (7% return) | Total Contributed | Tax-Free Growth |
|---|---|---|---|---|
| 22 | $625/mo (the $7,500 max) | $2,048,000 | $322,500 | $1,725,000 |
| 25 | $625/mo | $1,641,000 | $300,000 | $1,341,000 |
| 30 | $625/mo | $1,126,000 | $262,500 | $863,000 |
| 35 | $625/mo | $762,000 | $225,000 | $537,000 |
| 22 ($50/mo only) | $50/mo | $164,000 | $25,800 | $138,000 |
The last row is the most important: even $50/month starting at 22 produces $320,000 in tax-free wealth by retirement. The amount matters far less than the starting age. Every decade you wait roughly cuts your final balance in half.
Roth IRA Rules You Need to Know
The 5-year rule: To withdraw earnings tax-free, your Roth IRA must be at least 5 years old. This starts from January 1 of the first year you contribute. Open your Roth IRA as early as possible, even with a small contribution, to start this clock.
Contribution vs earnings withdrawals: You can withdraw your contributions (the money you put in, not the growth) at any time, penalty-free, for any reason. This makes the Roth IRA surprisingly flexible — it doubles as a last-resort emergency fund if needed. However, withdrawing earnings before 59½ triggers a 10% penalty plus income tax, so avoid touching the growth.
No Required Minimum Distributions (RMDs): Unlike 401(k)s and traditional IRAs, Roth IRAs have no mandatory withdrawal age. Your money can compound indefinitely — you can even pass it to heirs tax-free. This makes the Roth IRA excellent for estate planning in addition to retirement.
Contribution deadline: You can contribute to your Roth IRA up to the tax filing deadline for that year. For the 2026 tax year, the contribution deadline is April 15, 2027. This means you effectively have 15 months each year to fund your account.
Roth IRA vs 401k: Which Do You Prioritize?
You don’t have to choose — you should ideally use both. But here’s the right order of priority:
- First: Contribute to your 401(k) up to the employer match. This is a 100% immediate return — always take the free money first.
- Second: Max out your Roth IRA ($7,500 in 2026). Tax-free growth for decades outweighs almost everything else.
- Third: Return to your 401(k) and contribute more, up to the $24,500 limit.
- Fourth: Open a taxable brokerage account for any additional investing.
See our full beginner investing guide and Retirement Calculator to model how this order affects your long-term outcome.
What NOT to Do With Your Roth IRA
- Don’t leave it in cash. Opening a Roth IRA and leaving the money in the settlement fund (cash/money market) is one of the most common beginner mistakes. Cash earns 0–4% in a Roth IRA; an index fund earns 7–10% on average. Always buy an investment after funding.
- Don’t pick individual stocks. Over 90% of actively managed funds underperform the S&P 500 index over 15+ years. For a Roth IRA that you’ll hold for decades, a low-cost index fund is almost certainly the right choice.
- Don’t withdraw earnings early. Contributions can be withdrawn anytime penalty-free, but earnings withdrawn before age 59½ face a 10% penalty plus income tax. Let the account compound undisturbed.
- Don’t contribute more than the annual limit. Contributing over $7,500 in 2026 (if under 50) triggers a 6% excess contribution penalty per year until corrected. Set a reminder or automate contributions to stay within the limit.
- Don’t wait until you “have more money.” Starting with $50/month at 25 beats starting with $200/month at 35. Time is the most powerful variable in a Roth IRA. Open it today with whatever you have.
Roth IRA vs 401(k): A Side-by-Side Comparison
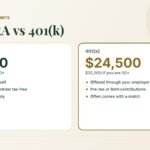
| Roth IRA | 401(k) | |
|---|---|---|
| Who offers it | You open it yourself | Your employer |
| 2026 limit | $7,500 | $24,500 |
| Employer match | None | Yes (free money) |
| Investment options | Anything (stocks, ETFs, funds) | Limited to plan menu |
| Tax on withdrawal | None (tax-free) | Taxed as income |
| Income limit | Yes ($161k single, 2026) | No |
| Early withdrawal of contributions | Anytime, penalty-free | 10% penalty before 59½ |
Use both. Get the 401(k) employer match first (free money), then max out the Roth IRA ($7,500), then return to the 401(k). Read our full 401(k) for Beginners guide to see how they work together. Use the Retirement Calculator to model the combined impact on your retirement balance.
Frequently Asked Questions About Roth IRAs
Can I open a Roth IRA with no money?
Yes — Fidelity, Schwab, and Vanguard all offer Roth IRAs with no minimum to open. You can open the account with $0 and add money whenever you’re ready. The important thing is to open the account now to start the 5-year clock, even if you can’t fund it immediately.
What if I earn too much for a Roth IRA?
If your income is above the 2026 limit ($168,000 single, $252,000 married), you can use the Backdoor Roth strategy: contribute to a non-deductible traditional IRA, then immediately convert it to a Roth IRA. This is completely legal and widely used by high earners. Consult a tax professional if your situation is complex.
Can I have both a Roth IRA and a 401(k)?
Yes — they’re completely separate accounts with separate contribution limits. You can max out both in the same year: $7,500 into your Roth IRA and $24,500 into your 401(k), for a combined $32,000 in tax-advantaged retirement savings in 2026.
Is a Roth IRA better than a savings account?
For money you won’t need for at least 5–10 years, yes — significantly better. A Roth IRA invested in index funds has historically returned 7–10% annually versus 4–5% in the best high-yield savings accounts. The tax-free growth is a massive additional advantage. But your Roth IRA is for retirement savings, not your emergency fund. Keep 3–6 months of expenses in a high-yield savings account before investing.
Can I withdraw from a Roth IRA before 59½?
Yes, but with important distinctions. Your contributions (the money you put in, not the gains) can be withdrawn at any time with no tax or penalty. Your earnings can only be withdrawn penalty-free after age 59½ and after the account is at least 5 years old. Withdrawing earnings early triggers a 10% penalty plus ordinary income tax.