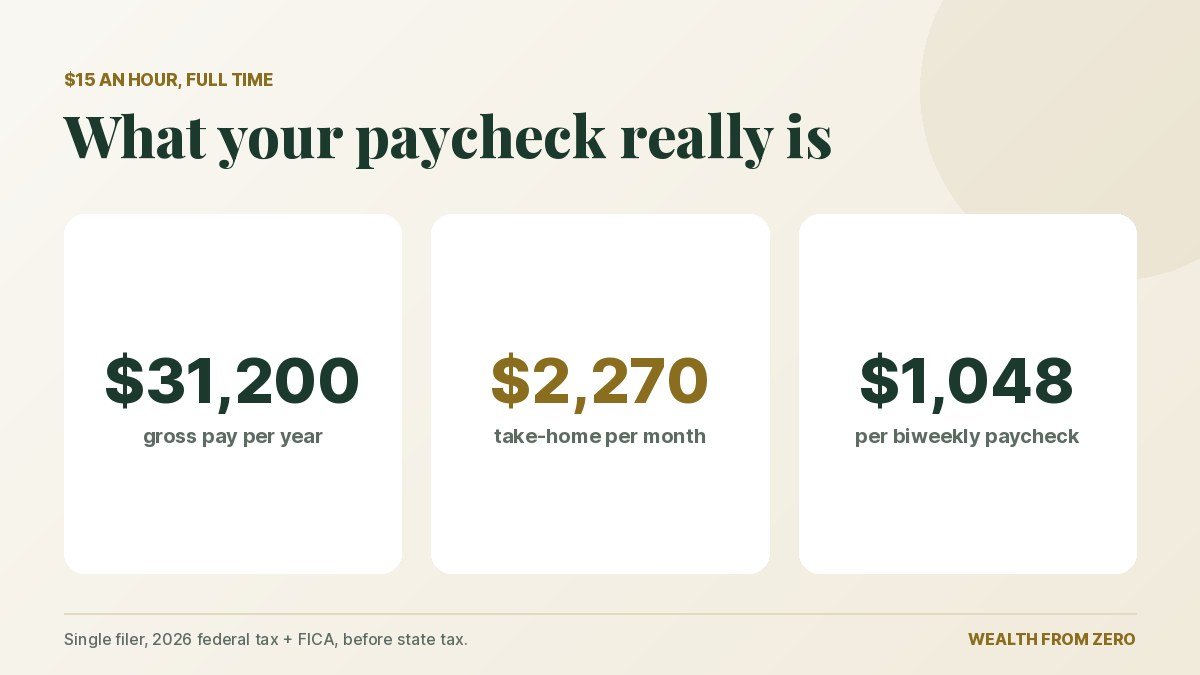
Short answer: working full time at $15 an hour, you earn about $31,200 a year, or roughly $2,270 a month after federal income tax and Social Security/Medicare (before any state or local tax). A workable budget on that is about 70% for needs, 20% for wants and 10% for savings until your pay goes up — the classic 50/30/20 split usually doesn’t fit at this income, and that’s okay.
Below: your real take-home pay at 40, 30 and 20 hours a week, a sample monthly budget with every line filled in, and the moves that make the biggest difference on $15 an hour.
What $15 an Hour Really Pays You
Your paycheck is smaller than “hours × $15” because of payroll taxes. Every worker pays 7.65% for Social Security and Medicare, plus federal income tax on income above the 2026 standard deduction of $16,100 for single filers (IRS Rev. Proc. 2025-32).
| Hours per week | Gross per year | Federal income tax | Social Security + Medicare | Take-home per month |
|---|---|---|---|---|
| 40 (full time) | $31,200 | about $1,560 | about $2,390 | about $2,270 |
| 30 | $23,400 | about $730 | about $1,790 | about $1,740 |
| 20 | $15,600 | $0 | about $1,190 | about $1,200 |
Single filer, no other income, standard deduction, before state and local taxes. If your state has an income tax, subtract a bit more. Full time works out to about $1,048 per biweekly paycheck or about $524 a week after federal taxes.
$15 an Hour Is How Much a Year, Month and Week?
| Full time (40 hours a week) | Before taxes | After federal taxes* |
|---|---|---|
| Per year | $31,200 | about $27,250 |
| Per month | $2,600 | about $2,270 |
| Every two weeks | $1,200 | about $1,048 |
| Per week | $600 | about $524 |
| Per day (8 hours) | $120 | about $105 |
*Federal income tax plus Social Security and Medicare, single filer, 2026. State and local taxes are extra in most states.
Why 50/30/20 Doesn’t Fit — and What to Use Instead
The 50/30/20 rule would give you about $1,135 a month for all needs. In most of the U.S. that won’t cover rent, food, transportation and insurance. Rather than feel like you’re failing a rule, use a split that matches your income now:
| Split | Needs | Wants | Savings / extra debt |
|---|---|---|---|
| 50/30/20 | $1,135 | $681 | $454 |
| 70/20/10 (realistic start) | $1,590 | $454 | $227 |
The goal is the order, not the exact numbers: savings come out first, needs get covered, and what’s left is yours to spend without guilt.
A Sample Budget on $2,271 a Month
Here is one realistic way to fill it in. Your rent and transportation will be different — swap in your own numbers in our budget calculator.
| Category | Monthly | Notes |
|---|---|---|
| Rent (your share) | $800 | A room or a shared apartment |
| Utilities + internet | $120 | Split with roommates |
| Groceries | $300 | Cooking most meals |
| Transportation | $200 | Gas + insurance, or a transit pass |
| Phone | $45 | Prepaid or low-cost carrier |
| Health costs | $100 | Premium share or out-of-pocket |
| Needs total | $1,565 | About 69% |
| Savings (automatic) | $230 | About 10% |
| Fun, eating out, clothes, gifts | $476 | About 21% |
| Total | $2,271 |
The Same Budget, Paycheck by Paycheck
Paid every two weeks? Here’s how two paychecks of about $1,048 can cover the month:
| Paycheck 1 ($1,048) | Paycheck 2 ($1,048) | ||
|---|---|---|---|
| Rent | $800 | Utilities + internet | $120 |
| Savings | $115 | Transportation | $200 |
| Groceries | $88 | Health costs | $100 |
| Phone | $45 | Groceries | $212 |
| Savings | $115 | ||
| Fun and everything else | $301 |
Two paychecks add up to about $2,096. The rest of the $2,271 monthly average comes from the fact that biweekly pay gives you 26 paychecks a year, not 24. Twice a year you get a third paycheck in the same month — about $1,048 that isn’t needed for regular bills. Sending both to savings or debt adds about $2,100 a year without changing your budget.
What Rent Looks Like on $15 an Hour
30% of $31,200 is $780 a month. In August 2026, the typical rent in even the cheapest large U.S. metros was above $1,340, according to the Zillow Observed Rent Index. Split with one roommate, it gets close:
| Metro area | Typical rent | Your half with a roommate |
|---|---|---|
| Louisville, KY | $1,348 | $674 |
| Oklahoma City, OK | $1,388 | $694 |
| Memphis, TN | $1,400 | $700 |
| San Antonio, TX | $1,422 | $711 |
| U.S. typical | $1,948 | $974 |
That’s why the sample budget above uses $800 for a room or shared apartment. See the income needed in all 50 largest metros in our rent affordability study.
7 Moves That Matter Most on $15 an Hour
1. Keep housing as low as you can
Rent is the line that decides everything else. A roommate often saves more than every small cut in this article combined. See our guide on how to save money on rent.
2. Budget by paycheck, not by month
If you’re paid every two weeks, assign each paycheck its bills: rent from one, everything else from the other. It stops the “where did it go?” feeling at the end of the month. Our guide to budgeting when you’re paid weekly shows the method step by step.
3. Pay yourself first, even if it’s small
Set up an automatic transfer of $50–$115 per paycheck into a separate savings account the day you’re paid. At $115 per biweekly check, you’d have about $3,000 after a year.
4. Build a $1,000 starter emergency fund
On a tight budget, a single surprise bill is what pushes people onto a credit card. A small cushion breaks that cycle. Then grow it toward one month of expenses. Our emergency fund calculator gives you a target.
5. Avoid high-interest debt
At 22% APR, a $1,000 card balance costs about $18 a month in interest — money that could have been a week of groceries. Use one card at most and pay it in full.
6. Grab the tax breaks you qualify for
If your job offers a retirement plan with a match, contribute at least enough to get it. Low- and moderate-income workers who save for retirement may also qualify for the Saver’s Credit (single filers with income up to $40,250 in 2026), a tax credit on top of the savings themselves.
7. Treat every raise as a budget event
When your pay goes up, send at least half of the raise to savings before you get used to it. Moving from $15 to $17 an hour full time adds about $4,160 a year before taxes.
If You Work Part Time
At 20–30 hours a week ($1,200–$1,740 a month), the same order applies, but housing usually has to be shared or with family, and the savings target may start at 5%. The most powerful lever is often more hours or a second income stream — see our list of ways to make extra money from home.
Frequently Asked Questions
Is $15 an hour enough to live on alone?
In many areas it’s tight to rent a one-bedroom alone on about $2,270 a month take-home. Most people at this income share housing, live with family, or live in a lower-cost area.
How much rent can I afford on $15 an hour?
A common guideline is 30% of gross income: about $780 a month on $31,200 a year. Many landlords also require gross income of about 40 times the monthly rent, which also points to roughly $780.
How much should I save on $15 an hour?
Start with 10% if you can — about $230 a month full time — and 5% if that’s too much. Consistency matters more than the amount.
Do I pay federal income tax on $15 an hour?
Full time, yes, but not much: about $1,560 a year as a single filer in 2026. Part time at 20 hours a week ($15,600 a year), your income is below the standard deduction, so federal income tax would be $0, though Social Security and Medicare still apply.
Sources
- IRS Rev. Proc. 2025-32 (2026 standard deduction and tax brackets)
- IRS Topic 751: Social Security and Medicare withholding rates
- IRS: Saver’s Credit
- Zillow Research: Zillow Observed Rent Index (ZORI)
Tax figures are estimates for a single filer with no other income, using 2026 federal rates. State and local taxes, benefits deductions and credits will change your exact take-home pay. This article is for education, not personal financial or tax advice.