The 50 30 20 rule is the most widely used budgeting method in the world — and for good reason. It takes your after-tax income and divides it into three simple categories: 50% for needs, 30% for wants, and 20% for savings and debt. No complicated spreadsheets. No tracking every coffee. Just three numbers that tell you exactly where your money should go.
This guide explains exactly how the 50 30 20 rule works, shows you real examples at different income levels, and gives you an honest answer about whether it will actually work for your situation.
According to the Bureau of Labor Statistics, the average US household spent about $78,535 in 2024 — roughly $6,545 a month.
What Is the 50 30 20 Rule?
The 50 30 20 rule is a budgeting framework created by US Senator Elizabeth Warren and her daughter Amelia Warren Tyagi in their 2005 book All Your Worth: The Ultimate Lifetime Money Plan. The idea is simple: split your monthly after-tax income into three buckets.
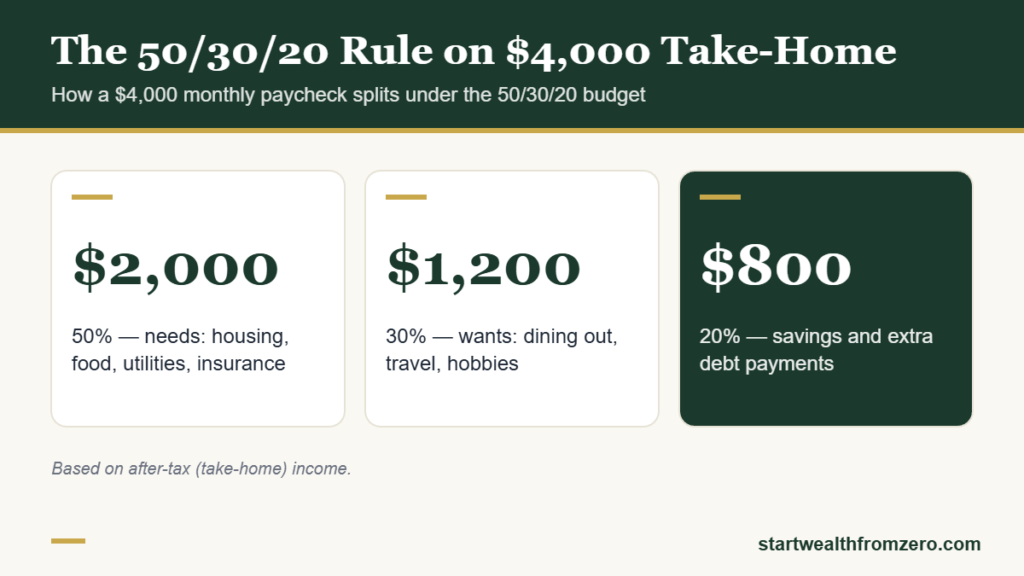
| Category | Percentage | What It Covers | Example ($4,000/month) |
|---|---|---|---|
| Needs | 50% | Rent, utilities, groceries, transport, insurance, minimum debt payments | $2,000 |
| Wants | 30% | Dining out, streaming, hobbies, gym, shopping, holidays | $1,200 |
| Savings & Debt | 20% | Emergency fund, investments, extra debt payments, retirement | $800 |
The rule works on after-tax income — the money that actually lands in your bank account after taxes and deductions. If your salary is $60,000 gross but you take home $4,200/month, you budget based on $4,200.
How the 50 30 20 Rule Works: Step by Step
Step 1: Calculate Your Monthly After-Tax Income
Add up every source of income after taxes: your salary, any freelance work, side hustle earnings, benefits. If your income varies month to month, use the average of the last 3 months. Always budget conservatively — use a lower number if you’re uncertain.
Step 2: Calculate Your 50% Needs Limit
Multiply your take-home pay by 0.5. That’s your maximum for essential expenses. List every fixed expense: rent or mortgage, car payment, insurance, utilities, phone, minimum loan payments, and groceries. If this total exceeds 50% of your income, you’ll need to make adjustments (more on that below).
Step 3: Allocate 30% to Wants
Multiply by 0.3. This is your spending money for everything non-essential — restaurants, Netflix, gym, clothes, hobbies, weekend trips. The 30% bucket gives you genuine spending freedom without blowing the budget. Crucially, you don’t have to track every purchase within it as long as you stay under 30%.
Step 4: Put 20% Toward Savings and Debt
Multiply by 0.2. Automate this transfer on payday so you never see the money in your spending account. Priority order: emergency fund first (up to $1,000), then high-interest debt, then retirement contributions, then longer-term savings goals. Use our Savings Calculator to see how this 20% compounds over time.
50 30 20 Rule: Real Examples at Different Income Levels
Here’s exactly how the 50 30 20 rule breaks down across four real income levels:
| Monthly Take-Home | 50% Needs | 30% Wants | 20% Savings/Debt | Annual Savings |
|---|---|---|---|---|
| $2,500 | $1,250 | $750 | $500 | $6,000/year |
| $3,500 | $1,750 | $1,050 | $700 | $8,400/year |
| $5,000 | $2,500 | $1,500 | $1,000 | $12,000/year |
| $7,500 | $3,750 | $2,250 | $1,500 | $18,000/year |
| $10,000 | $5,000 | $3,000 | $2,000 | $24,000/year |
Someone earning $5,000/month take-home who follows the 50 30 20 rule faithfully will save $12,000 per year — enough to build a full emergency fund, make meaningful progress on debt, or max out a Roth IRA ($7,500 in 2026) with money to spare.
Needs vs Wants: The Full Breakdown
The most common source of confusion with the 50 30 20 rule is deciding what’s a need vs a want. Here’s a definitive guide:
| Expense | Category | Why |
|---|---|---|
| Rent / mortgage | ✅ Need | Essential shelter |
| Basic groceries | ✅ Need | Required for survival |
| Utilities (electricity, water) | ✅ Need | Non-negotiable basics |
| Car payment (if needed for work) | ✅ Need | Required for income |
| Health insurance | ✅ Need | Essential protection |
| Minimum debt payments | ✅ Need | Avoids penalties and credit damage |
| Phone (basic plan) | ✅ Need | Required for work and safety |
| Dining out / takeaway | ❌ Want | Food at home covers the need |
| Netflix / streaming | ❌ Want | Entertainment, not essential |
| Gym membership | ❌ Want | Nice to have, not required |
| Premium phone plan | ❌ Want | Basic plan is the need; premium is a want |
| Holidays / travel | ❌ Want | Discretionary |
| Clothing beyond basics | ❌ Want | Some clothing is a need; fashion is a want |
| Extra debt payments (above minimum) | 💰 Savings/Debt | Goes in the 20% bucket |
| Retirement contributions | 💰 Savings/Debt | Part of the 20% |
A note for 2026: According to the Bureau of Labor Statistics Consumer Expenditure Survey, the average American household now spends around 34% of after-tax income on housing alone — above the 50% needs threshold if you add food, transport, and utilities. This is why many financial experts now suggest a 60/20/20 split as a more realistic starting point for people in high-cost areas.
What If My Needs Cost More Than 50%? (The Honest Answer)
This is where most guides shy away from the truth. For many people — especially in high cost-of-living cities — needs genuinely cost more than 50% of income. Rent alone can consume 40-50% of take-home pay in cities like high-cost cities like New York, San Francisco or Boston. That’s not a budgeting failure — it’s a housing market reality.
If your needs exceed 50%, you have two options:
- Adjust the percentages: Try 60/20/20 or 65/20/15 to fit your reality. The key ratios to protect are the 20% savings and at least some wants allocation so the budget is sustainable.
- Reduce fixed costs: A cheaper apartment, refinancing a car loan, switching insurance providers, or moving to a lower cost-of-living area are the only real ways to fix a structural needs problem.
The 50 30 20 rule is a framework, not a law. Adapt it to your income and cost reality.
Other situations where the rule needs adjusting:
- High debt burden. If you have $30,000+ in credit card or student loan debt at high interest, temporarily shift to 50/10/40 (40% to debt payoff) until the debt is cleared.
- Very low income. On $2,000/month take-home, basic needs may consume 70%+, leaving nothing for wants. Zero-based budgeting works better at lower incomes. See our Zero-Based Budgeting guide.
- Building wealth aggressively. If your goal is early retirement or financial independence, 20% savings isn’t enough. Push toward 30-50% savings rate. See our early retirement guide.
50 30 20 Rule vs Other Budgeting Methods
| Method | Split | Time to Set Up | Control Level | Best For |
|---|---|---|---|---|
| 50 30 20 Rule | 3 categories | 10 minutes | ⭐⭐⭐ Moderate | Beginners, people who hate detailed budgets |
| Zero-Based Budget | Every dollar assigned | 45-60 minutes | ⭐⭐⭐⭐⭐ Maximum | Debt payoff, tight budgets, full control |
| Pay Yourself First | Save first, spend rest | 5 minutes | ⭐⭐ Low | Good savers who struggle with the detail |
| Envelope Method | Cash by category | 30 minutes | ⭐⭐⭐⭐ High | Overspenders on variable categories |
| 80/20 Rule | Save 20%, spend 80% | 5 minutes | ⭐ Very low | High earners who just want to save |
50 30 20 Rule With Irregular Income
If you freelance, work on commission, or have a variable income, the 50 30 20 rule still works — you just apply it differently. Use the lowest month from your last 6 as your baseline budget income. Apply the 50/30/20 split to that baseline only. When higher-income months arrive, immediately assign every extra dollar: debt first, then emergency fund, then sinking funds. Never let extra income sit unallocated — it disappears.
Example: Your average monthly income over 6 months is $4,200, but your lowest month was $2,800. Budget on $2,800. When the $4,200 month arrives, the extra $1,400 goes straight to a priority list you’ve already written.
How to Make the 50 30 20 Rule Actually Stick
The rule fails for most people not because of the percentages — but because they don’t automate it. Here’s the system that works:
- Automate the 20% on payday. Set up an automatic transfer to a separate savings account the moment your salary lands. What you don’t see, you don’t spend.
- Use a separate account for wants. Transfer exactly 30% to a second account for discretionary spending. When it’s gone, it’s gone — no guilt, no confusion.
- Pay fixed needs from your main account. Bills, rent, and essentials come out of your primary account automatically.
- Check weekly, not daily. A 5-minute weekly review keeps you on track without becoming obsessive.
Use our Emergency Fund Calculator to calculate your exact savings target within the 20% bucket, and our Debt Payoff Calculator to model how quickly you’ll clear debt by allocating part of that 20% to extra payments.
The 50 30 20 Rule: Common Mistakes
| Mistake | What Goes Wrong | Fix |
|---|---|---|
| Using gross income instead of take-home | Budget is based on money you never see | Always use after-tax income |
| Putting subscriptions in “needs” | The 50% fills up with wants in disguise | Netflix, Spotify, gym = wants (30%) |
| Skipping the 20% when money is tight | No savings progress, ever | Even $50/month to savings beats $0 |
| Not adjusting for your city’s cost of living | Budget collapses immediately | Adapt percentages to your reality |
| Tracking wants obsessively | Budget becomes exhausting | Transfer the 30% and stop tracking |
Is the 50 30 20 Rule Right for You?
The 50 30 20 rule is ideal if you want a simple system that’s actually sustainable. It’s not the most powerful budgeting method — zero-based budgeting will find more money — but it’s the one most people will actually follow for more than 3 weeks. That consistency is worth more than theoretical perfection.
It works best for people with stable incomes, moderate cost of living, and no urgent debt crisis. If you’re in serious debt or your needs genuinely exceed 60% of income, consider starting with our beginner’s budgeting guide first, then moving to zero-based budgeting for maximum debt payoff speed.
What the 50 30 20 Rule Does (and Doesn’t) Do
Being honest about the limitations of the 50 30 20 rule is just as important as understanding its strengths. Here’s the full picture:
| What the 50 30 20 Rule Does Well | What It Doesn’t Do |
|---|---|
| ✅ Simple enough to start immediately | ❌ Won’t maximize debt payoff speed |
| ✅ Prevents lifestyle creep | ❌ Doesn’t work if needs genuinely exceed 50% |
| ✅ Sustainable long-term | ❌ Provides no detail on where wants money goes |
| ✅ Flexible — adapt percentages to your life | ❌ Not ideal for people with complex financial situations |
| ✅ Works for any income level | ❌ The 30% wants can feel like too much or too little |
| ✅ Builds the savings habit automatically | ❌ Doesn’t specify how to split the 20% (savings vs debt) |
For the 20% savings bucket specifically: if you have high-interest debt (credit cards, personal loans above 8%), pay that down first before saving. The guaranteed return of eliminating 20% APR debt beats any investment return. Once high-interest debt is gone, split the 20% between emergency fund, retirement, and other goals.
50 30 20 Rule: The Bottom Line
The 50 30 20 rule works because it’s simple enough to actually use. Split your after-tax income: 50% to needs, 30% to wants, 20% to savings and debt. Automate the 20% on payday. Transfer the 30% to a separate spending account. Let the 50% cover your essentials.
Do this for 6 months and you’ll have a starter emergency fund, real progress on debt or savings, and a clear picture of where your money goes — without tracking every transaction. That’s the power of the 50 30 20 rule.
Ready to go further? Use our free Compound Interest Calculator to see what consistently saving 20% of your income will grow to over 10, 20, or 30 years.
Related: How much should you save each month? Targets by age and income
Frequently Asked Questions About the 50 30 20 Rule
Here are the most common questions people ask about the 50 30 20 rule — answered directly.
Who invented the 50 30 20 rule?
The 50 30 20 rule was created by US Senator Elizabeth Warren and her daughter Amelia Warren Tyagi in their 2005 book All Your Worth: The Ultimate Lifetime Money Plan. Warren, a Harvard bankruptcy expert, designed it to give everyday people a simple framework after studying why middle-class families kept going broke despite rising incomes.
Does the 50 30 20 rule use gross or net income?
Always net (after-tax) income. Your gross salary includes taxes you never receive. Budget only on the money that actually hits your bank account.
What if I can’t keep needs under 50%?
You’re not alone — especially in high cost-of-living areas. Adjust the percentages to 60/20/20 or whatever fits your reality. The most important number to protect is the 20% savings. Reducing it makes everything else harder.
Where does debt repayment go in the 50 30 20 rule?
Minimum payments on debt count as needs (50%). Any extra debt payments above the minimum go into the savings/debt bucket (20%). Paying extra on debt is a form of guaranteed return — every dollar of credit card debt paid at 20% APR saves you 20% interest.
Is the 50 30 20 rule better than zero-based budgeting?
Depends on your goals. The 50 30 20 rule is simpler and more sustainable for most people. Zero-based budgeting is more powerful for aggressive debt payoff or when you need to find every possible dollar. Many people start with 50 30 20 and switch to zero-based when they’re ready to get serious.
Related resources: budgeting app, savings calculator, zero-based budgeting, sinking fund.
Related resources: how to make a budget.
Related resources: how to stop impulse buying.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always consult a qualified professional for personalized financial guidance.