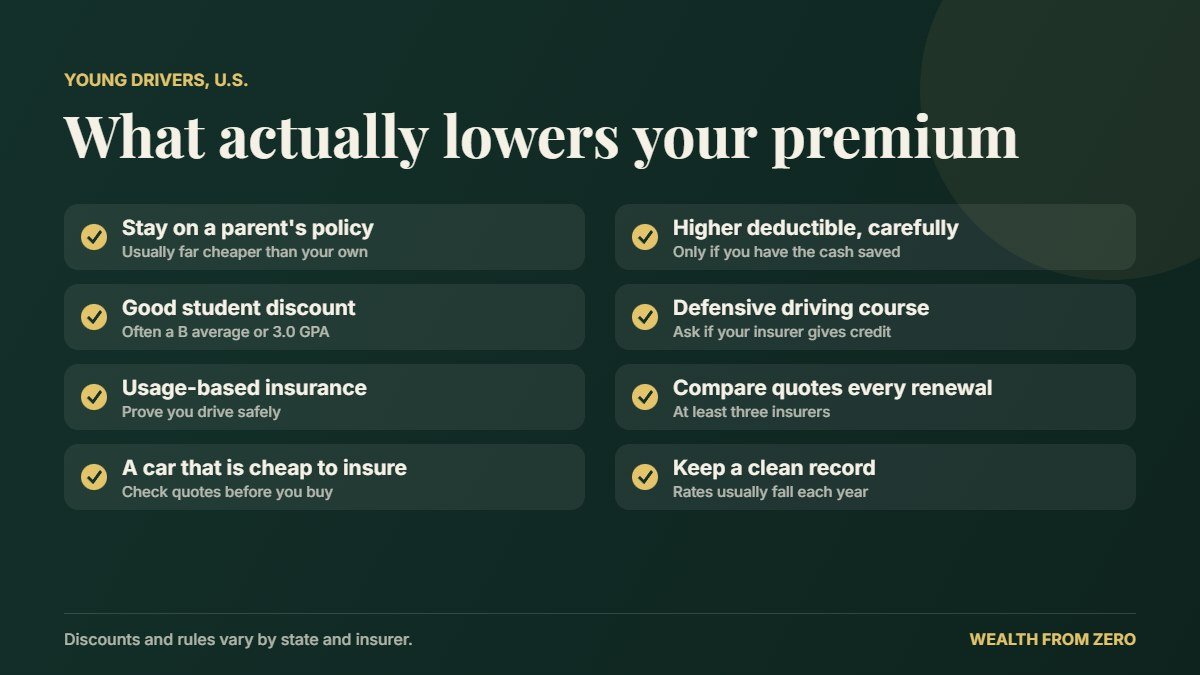
Car insurance is one of the biggest fixed costs for young drivers — often more than the car payment itself. You can’t change your age or driving experience, but you can change almost everything else insurers look at: which car you drive, how much coverage you buy, which discounts you claim, and how often you shop around.
This guide is for drivers in the US, where requirements and discounts vary by state and insurer. The 11 tips below are ordered roughly by how much they tend to save. To see how the savings fit into your wider plan, try our Budget Calculator.
Why Young Drivers Pay More
Insurers price a policy on how likely you are to file a claim, and inexperience is the biggest risk they see. According to the CDC, drivers aged 16 to 19 have a fatal crash rate almost three times as high as drivers 20 and older per mile driven, and risk is highest in the first months after getting a license. That is why premiums usually come down as you build a few years of clean driving history.
Some of the factors insurers use are out of your hands for now. Many are not:
| Rating factor | Can you change it? | What to do |
|---|---|---|
| Age and years licensed | Not right now | Rates usually fall as you build clean driving years |
| Driving record | Yes, over time | Avoid tickets and at-fault claims (tip 11) |
| The car you drive | Yes | Get insurance quotes before you buy (tip 4) |
| Coverage and deductible | Yes | Match coverage to the car’s value (tips 5, 9 and 10) |
| Discounts | Yes | Good student, telematics, courses (tips 2, 3, 6 and 7) |
| Where the car is kept | Rarely | Always give the real address; misstating it is misrepresentation |
| Credit-based insurance score | Yes, slowly | Not allowed for auto pricing in some states (tip 11) |
1. Stay on Your Parents’ Policy (If You Can)
For most young drivers, being added to a parent’s multi-car policy is far cheaper than buying a separate policy. You’ll usually need to live at the same address, and the car you drive should be listed. Be accurate about who mainly drives which car — listing a parent as the main driver of a car you actually drive most of the time can be treated as misrepresentation and may lead to a denied claim.
2. Get the Good Student Discount
Many insurers discount premiums for full-time students with good grades — commonly a B average or 3.0 GPA, though the exact rules vary. Some also offer a discount if you’re at college far from home without a car. Ask your insurer what documentation it needs.
3. Try Usage-Based (Telematics) Insurance
Most major insurers offer programs that track your driving through an app or a plug-in device — things like speed, hard braking, phone use and time of day. Safe drivers can earn a discount, which is one of the few ways a young driver can prove they’re lower risk than their age suggests. Read the terms: with some programs, risky driving can raise your rate.
4. Choose a Car That’s Cheap to Insure
The car itself has a big effect on your premium. Sensible, safe, lower-powered cars with good safety ratings generally cost less to insure than sports cars, luxury models or cars that are expensive to repair or often stolen. Get insurance quotes before you buy — two similar-priced cars can have very different insurance costs. Our guide on saving for a car covers the purchase side.
5. Raise Your Deductible — Carefully
Your deductible is what you pay toward a collision or comprehensive claim before insurance kicks in. Raising it (for example, from $500 to $1,000) usually lowers your premium. The catch: you need that amount available in savings if you have an accident. A higher deductible only saves money if you can actually afford it — which is one more reason to keep an emergency fund.
6. Take a Defensive Driving Course
Many insurers — and some states — offer a discount for completing an approved defensive driving course. Check with your insurer which courses qualify and how long the discount lasts before you sign up.
7. Claim Every Discount You Qualify For
- Pay in full: paying the 6- or 12-month premium upfront often costs less than monthly installments.
- Autopay and paperless billing: small discounts that add up.
- Bundling: combining auto with renters or homeowners insurance from the same company.
- Safety and anti-theft features: airbags, anti-lock brakes and anti-theft systems can earn discounts.
- Low mileage: if you drive little, some insurers offer lower rates or pay-per-mile policies.
8. Compare Quotes at Every Renewal
Prices for the same driver and car can vary a lot between insurers, and loyalty rarely pays. Get at least three quotes — from insurers directly, through an independent agent who works with several companies, or both — each time your policy renews, and compare the same coverage and deductibles side by side.
9. Reconsider Collision and Comprehensive on an Older Car
Collision and comprehensive cover damage to your own car. If your car is worth relatively little, the cost of that coverage may not be worth it. A common rule of thumb: if the annual cost of collision and comprehensive is more than about 10% of the car’s value, consider dropping them. If you have a car loan or lease, the lender will usually require them.
10. Don’t Cut Liability Coverage to the Bone
Every state (except New Hampshire, which has different rules) requires minimum liability coverage, but state minimums are often low compared with the cost of a serious accident. If you cause damage beyond your limits, you can be personally responsible for the rest. Saving on premiums should come from discounts and smart choices — not from being underinsured.
11. Build Your Credit and a Clean Record
In most states, insurers can use a credit-based insurance score to set rates (California, Hawaii and Massachusetts prohibit this for auto insurance). Paying bills on time and keeping card balances low can help — see our guide on building credit from scratch. Meanwhile, every year without tickets or at-fault accidents typically brings your premium down.
Before You Buy: A Quick Quote Checklist
- Get at least three quotes with the same liability limits and deductibles, so you compare like with like.
- Look up your state’s minimum liability requirements through your state insurance department. The minimum is a legal floor, not a recommendation.
- Ask each insurer to list every discount it applied, and which others you could get with proof (a transcript, a course certificate).
- Confirm who is listed as the main driver of each car, and that it matches reality.
- Ask your state insurance department about an insurer’s complaint record if you have not heard of the company.
- Shop again at every renewal, and after a move, a new car or a few clean years.
Frequently Asked Questions
Why is car insurance so expensive for young drivers?
Insurers price by risk, and drivers in their teens and early 20s have higher crash rates than more experienced drivers. Premiums usually fall as you build a clean driving record and get older, with noticeable drops often seen by the mid-20s.
Is it cheaper to stay on my parents’ car insurance?
Usually, yes — adding a young driver to a parent’s multi-car policy tends to cost less than a separate policy. You generally need to live at the same address, and the car you drive should be listed on the policy. Being honest about who the main driver of each car is matters: listing a parent as the main driver of a car you mostly drive can be treated as misrepresentation.
What is a good student discount?
Many insurers offer a discount to full-time students who keep good grades — often a B average or a 3.0 GPA, though requirements vary. You typically need to send a transcript or report card to qualify.
Should I choose a higher deductible?
A higher deductible usually lowers your premium, but you’ll pay more out of pocket if you make a claim. Only choose a deductible you could cover from your savings tomorrow.
Do insurers use my credit score?
In most states, insurers can use a credit-based insurance score when setting rates. California, Hawaii and Massachusetts prohibit using credit for auto insurance pricing, and some other states limit it. Building good credit can help lower premiums where it’s allowed.
Further reading: NAIC consumer insurance resources and your state insurance department’s website, which lists minimum coverage requirements.
Sources
- CDC: Risk Factors for Teen Drivers (citing IIHS fatality data)
- NAIC: Credit-Based Insurance Scores
- NAIC: Directory of state insurance departments
Disclaimer: This article is for informational purposes only. Coverage requirements, discounts and pricing rules vary by state and insurer.